

Title: Waterfront Home Insurance in Vero Beach FL
Caption: Waterfront homes in Vero Beach offer exceptional views, but they need a much more deliberate insurance strategy than inland properties.
You might be reading this from a back patio off the Indian River Lagoon, or from a kitchen table a few blocks from Ocean Drive, staring at an insurance quote that feels far more complicated than it should. The house is exactly what you wanted. The insurance part is where the stress starts.
That stress is justified. Waterfront Home Insurance in Vero Beach FL isn't just "regular homeowners insurance with a higher premium." A key problem is that many owners don't discover the biggest gap until after a storm, when they learn wind and flood are handled differently, often by different policies, different adjusters, and different deductibles.
If you own near the river, on the island, or anywhere close enough to worry about surge, rain intrusion, and hurricane-force wind, you need a clean understanding of what you're buying. Otherwise, you're paying a lot and still leaving the worst exposure open.
Table of Contents
- The Dream and the Reality of Vero Beach Waterfront Living
- The Two Policies You Absolutely Must Understand
- Decoding Wind Damage and Hurricane Deductibles
- Essential Coverages and Recommended Endorsements
- Proactive Steps to Lower Your Insurance Costs in Vero Beach
- Navigating a Claim After the Storm Passes
- Why an Independent Agent Is Your Best Ally
- Frequently Asked Questions About Vero Beach Waterfront Insurance
The Dream and the Reality of Vero Beach Waterfront Living
A waterfront home in Vero Beach sells itself. Sunrise over the Atlantic. Evening light on the lagoon. A dock out back, a breeze off the water, and a house that feels like the reason people work hard in the first place.
Then the insurance quote lands.
For a lot of buyers, that's the moment the romance meets the math. The home looked straightforward during showings. The policy package doesn't. You see separate terms for wind, flood, deductibles, exclusions, and optional endorsements for things you assumed were already covered. If you're looking near Johns Island, the barrier island, or along riverfront stretches inland, that confusion gets expensive fast.
What catches new waterfront owners off guard
The biggest shock usually isn't that insurance costs more. Such an increase is often anticipated. What surprises is learning that "hurricane damage" isn't one simple coverage bucket.
A storm can break windows with wind, push water through doors with surge, and soak interiors through openings that trigger arguments over cause. That means your claim may depend less on whether a hurricane hit and more on exactly how the damage happened.
Waterfront insurance problems usually start with one bad assumption: "I have homeowners insurance, so hurricane damage is covered."
That's why owners shopping barrier island home insurance in Vero Beach FL need more than a quote. They need the policy structure explained in plain English.
My advice before you buy or renew
Treat waterfront insurance as part of the property itself. If the house sits near open water, insurance isn't a paperwork step at closing. It's part of the carrying cost, part of the risk profile, and part of the decision about whether the home still fits your budget.
If you approach it that way from day one, you make better choices on coverage limits, deductibles, and flood protection. If you don't, you're gambling on details that matter most after a storm.
The Two Policies You Absolutely Must Understand
A hurricane hits overnight. By sunrise, part of your roof is open, rain has soaked the upstairs ceiling, and water has also pushed in at the ground floor from the river or surge. You now have two damage paths, and they do not go through one policy.
That is the point many waterfront owners in Vero Beach miss until claim time. Your homeowners policy and your flood policy handle different causes of loss. If you own near the barrier island, along the Indian River Lagoon, or anywhere water can rise fast during a storm, you need both policies understood before the first watch is issued.
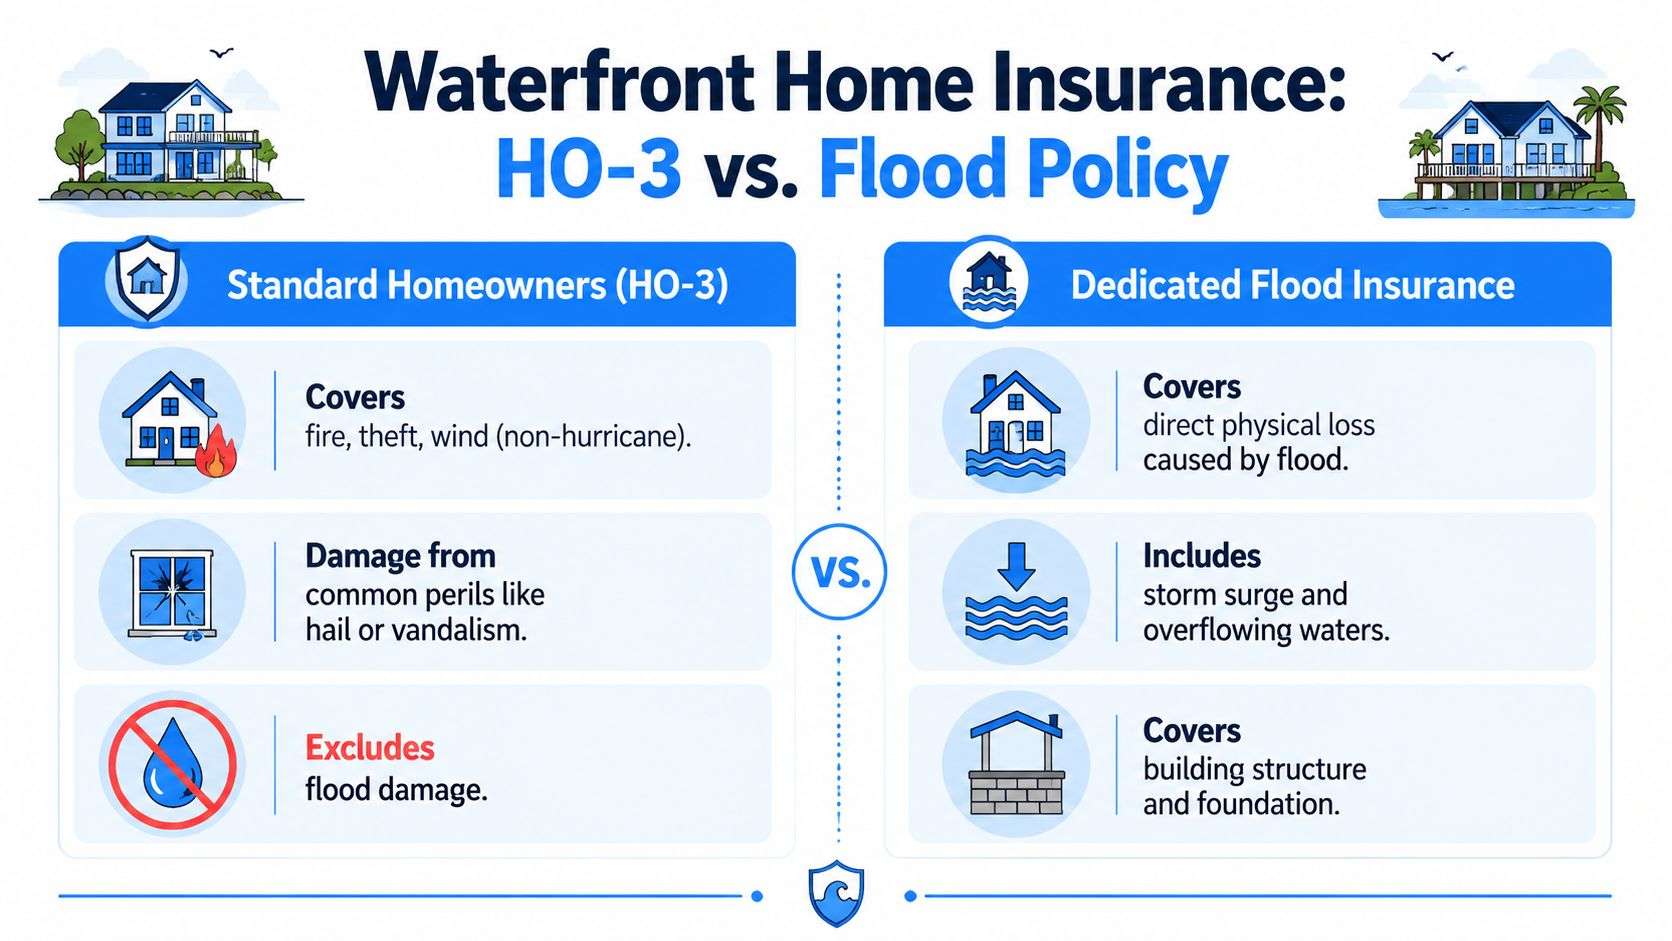
What each policy is actually for
Your homeowners policy usually covers covered wind-related damage, subject to exclusions, conditions, and deductibles. If wind damages the roof, breaks windows, or lets rain enter through a storm-created opening, that claim usually starts there.
Flood coverage is separate. It is built for rising water, storm surge, tidal overflow, and water entering from the outside at ground level. Standard homeowners insurance generally does not pick up that kind of loss, which is why a separate flood insurance policy in Vero Beach FL is part of basic waterfront planning, not an add-on for worst-case thinkers.
Why this separation matters after a Vero Beach hurricane
One storm can damage the same house in two different ways. That is where claims get messy.
If a storm near Ocean Drive rips shingles off and rain comes through the roof, that points toward the homeowners side. If surge or floodwater later enters the first floor from outside, that points toward the flood side. Same hurricane. Different causes. Different adjusters in many cases. Different deductibles and limits.
Owners get into trouble when they say, "I have hurricane coverage," as if that settles it. It does not. The question that matters is much more specific: what damage came from wind, what came from rising water, and how much of each loss are you paying yourself before insurance responds?
The coverage gap high-value waterfront owners need to check
Flood insurance has limits, and those limits may not match the cost to rebuild a higher-value waterfront home. That matters a lot in Vero Beach, where many homes near the water have finishes, elevations, and repair costs that push well past standard assumptions.
If your flood limit is too low, the claim can be approved and still leave you short. I see owners focus on getting flood coverage in place, then fail to check whether the amount is enough for the house they own. That is a costly mistake.
My advice: Stop asking, "Am I covered for a hurricane?" Ask, "Which policy pays for wind, which policy pays for flood, what are my limits, and what is my out-of-pocket exposure on each one?"
Ask that before storm season, not after water marks are already on the drywall.
Decoding Wind Damage and Hurricane Deductibles
A hurricane hits Vero Beach overnight. By morning, your roof is peeled back on the east side, rain has soaked the upstairs ceilings, and the deductible on your wind claim is far larger than you expected. That surprise hurts almost as much as the storm.
For waterfront homes, the key question is not whether wind coverage exists. The question is how much cash you must put in before the policy starts paying for covered wind damage. In this market, that number is often tied to a hurricane deductible set as a percentage of your dwelling coverage, not a small flat deductible you can absorb without planning.
Why percentage deductibles matter so much on waterfront homes
A percentage deductible changes the math fast. The higher the insured value of the house, the higher your out-of-pocket cost after a named storm triggers that deductible.
That is why I push clients to stop judging a policy by premium alone. A lower annual cost can hide a deductible that becomes painful after a storm, especially on barrier island homes or higher-value properties near the river and beach. If your house needs urgent tarping, water extraction, temporary housing, and immediate contractor deposits, cash flow matters on day one.
This also ties directly back to the wind-versus-flood split. Your homeowners policy may respond to covered wind damage, but the hurricane deductible applies before that payment starts. Flood is a separate claim path. If wind opens the roof near Riomar and rain enters from above, your wind deductible is part of the problem. If rising water later enters the ground floor from outside, that is a different coverage question entirely.
Why one Vero Beach quote can look cheap and another does not
Pricing moves for good reason. Homes closer to the ocean, older homes, and houses with weaker wind-mitigation features usually cost more to insure for wind. Rebuilding a waterfront property also tends to cost more because the materials, labor, access, and finish level leave less room for shortcuts.
The local Vero Beach market example shows that newer mainland homes can start around $3,000 per year, while older homes or homes closer to the beach can run about $6,000 to $10,000 per year, especially on the island. The same discussion notes that hurricane deductibles are commonly structured as a percentage of dwelling coverage, which is why quote comparisons need more than a glance at premium alone, according to this Vero Beach market discussion.
My recommendation on choosing the deductible
Pick a hurricane deductible you can fund.
I do not mean a deductible that looks acceptable during quoting. I mean one you can pay while also covering temporary repairs, hotel costs, food, fuel, and the gap between when the storm passes and when claim money arrives. If writing that check would force you to borrow, sell investments at the wrong time, or delay repairs, the deductible is too high.
For many waterfront owners, the smart move is simple. Pay a bit more in premium and keep the hurricane deductible at a level that will not wreck your recovery. After a storm, the goal is not winning the quote. The goal is protecting your house and staying in control of the claim.
Essential Coverages and Recommended Endorsements
A waterfront policy shouldn't stop at "dwelling plus liability." That's a base model. Waterfront property needs a sharper build.
The house itself is exposed to wind, water, corrosion, and code issues. The property around it often includes features that standard forms may limit, exclude, or treat narrowly. If you don't inspect those details before binding coverage, you're setting up unpleasant surprises later.
What needs close attention
Start with the core pieces and read them as if a storm already happened.
- Dwelling coverage: This has to reflect what it would realistically take to repair or rebuild the structure with comparable workmanship and materials.
- Other structures: Detached garages, fences, and similar structures need review. On waterfront property, owners often assume this bucket also solves every exterior feature issue. It may not.
- Personal property: A furnished waterfront home can carry far more value inside than owners remember during quoting.
- Personal liability: Waterfront homes bring visitors, contractors, pool exposure, and more reasons not to skimp here.
Endorsements I push clients to review carefully
Some endorsements matter more on older coastal homes than on newer ones, but every waterfront owner should review them.
| Coverage area | Why it matters for waterfront homes |
|---|---|
| Ordinance or law | Older homes may need upgrades to current building requirements after a covered loss |
| Increased cost of construction | Rebuilding can trigger added expense beyond basic repair work |
| Water backup or similar protection | Not the same as flood coverage, but still worth reviewing for non-flood water events |
| Scheduled valuables | Jewelry, art, and specialty items are common in second homes and higher-value residences |
The property features owners assume are covered
Docks, seawalls, boat lifts, exterior hardscape, and specialty structures deserve direct questions. Don't assume they're covered just because they're attached to the enjoyment of the home. Ask how the policy treats each one. Ask whether limits are built in, restricted, or excluded. Ask what documentation the carrier wants.
If a feature would be expensive to rebuild and it's outside the main living area, verify it in writing. Assumptions don't survive claim time.
My opinion is simple. A waterfront insurance review should feel more like a property audit than a quick quote request. If nobody is asking about your dock, seawall, older roof, or code exposure, the review isn't thorough enough.
Proactive Steps to Lower Your Insurance Costs in Vero Beach
A lot of waterfront owners in Vero Beach pay more than they should because they treat insurance like a once-a-year bill instead of a property file that needs upkeep. That gets expensive fast on homes near the river, the canals, and the barrier island, where one weak point can change how an insurer prices the risk.

The goal is simple. Give the carrier solid proof that your home is better protected and easier to evaluate. On waterfront property, that means updated inspections, clear documents, and smart choices about what you keep on the house and what you keep on the policy.
A local discount owners should not ignore
Vero Beach participates in FEMA's Community Rating System. That can help reduce flood insurance costs for eligible policyholders, as noted earlier in the article. If you own in a flood-prone area near the Indian River Lagoon or closer to the ocean, ask whether that credit is already reflected in your flood premium. Do not assume it is.
That discount only helps the flood side of the bill. It does nothing to fix a weak wind profile, and that distinction matters after a hurricane. Lower cost is good. Lower cost with the wrong protection is a bad deal.
What usually lowers cost without weakening coverage
Start with the items underwriters care about:
- Get a current wind mitigation inspection: Old paperwork leaves discounts on the table. If your roof covering, roof deck attachment, roof-to-wall connection, or opening protection has improved, make sure the file shows it.
- Keep your elevation documentation current: Flood pricing depends heavily on how the structure sits relative to expected water levels. If your records are outdated or missing, fix that before renewal.
- Upgrade the openings that fail first: Impact glass, rated shutters, and reinforced garage doors can improve the home and support better underwriting results.
- Choose your deductible on purpose: A higher deductible can trim premium, but only if you can write that check after a storm. On waterfront homes, that decision needs to match your cash reserves, not your optimism.
- Document every major improvement: Roof replacement, window upgrades, electrical work, plumbing updates, and elevation-related work should all be easy to prove with permits, invoices, and photos.
Preparation matters too. If you want a practical checklist to secure your home before a hurricane, use one before watches go up, not the night before landfall. Early preparation helps prevent damage, and it also gives you cleaner records if you end up filing a claim.
Mitigation work is not just maintenance. It gives you an advantage in the insurance conversation.
My advice is blunt. Review your policy and inspections every year, especially if you have made upgrades or bought an older waterfront home near A1A, the Moorings, or along the lagoon. Passive renewals are expensive. They also leave owners exposed to the bigger problem in Vero Beach after a hurricane: paying one premium for wind, another for flood, and then finding out too late that the discount they chased did nothing to close the gap between those two claims.
Navigating a Claim After the Storm Passes
The hours after a hurricane are chaotic. During these moments, preparation pays off.
If your waterfront home takes damage, your first job isn't arguing coverage. It's safety. Stay out of standing water, downed power areas, and unstable sections of the house. Once the property is safe to enter, your next priority is preserving evidence before cleanup destroys it.
What to do first
Take these steps in order:
- Make the home safe if you can do it safely: Tarp openings, shut off utilities if needed, and prevent further damage where possible.
- Notify all relevant carriers promptly: If both wind and flood may be involved, report both claims.
- Document before moving things: Take wide shots, close-ups, exterior views, interior views, and damaged personal property.
- Keep a written timeline: Note when the storm hit, when water entered, when roof damage was first visible, and what temporary repairs you made.
Why cause of loss matters so much
For waterfront homes, claim disputes often turn on one issue. What caused the damage first, and how did it enter the home?
If windows failed from wind and rain entered from above, that can point one direction. If rising water entered from outside at floor level, that points another. In mixed-loss situations, the details matter. Your photos, videos, and notes help establish the sequence.
Document the line where water reached, the direction debris came from, and every visible roof or opening failure before contractors start cleanup.
Bring in the right documentation support
A roof evaluation can become important quickly if the house took obvious wind impact. If you need a technical opinion on storm-related roof conditions, a professional roof inspection can help you organize facts and understand what you're looking at before repairs move forward.
Keep every receipt for emergency materials, temporary labor, and protective work. Save emails. Save text messages. Save adjuster contact information. Save photographs in more than one place.
The owners who struggle most after storms often aren't the ones with the worst damage. They're the ones with the weakest documentation.
Why an Independent Agent Is Your Best Ally
The storm is over. Your dock is twisted, water is sitting in the garage, and part of the roof peeled back overnight. Now the question that decides your claim is the one waterfront owners in Vero Beach often misunderstand until it is too late. Was the damage caused by wind, by rising water, or by both?
That is why an independent agent matters.

A waterfront policy review should never stop at premium. It should test how your protection will hold up when a real claim hits, especially on homes near the barrier island, along the Indian River Lagoon, or in neighborhoods where wind and water can affect the same property in the same storm.
A good independent agent looks at the full setup. Homeowners coverage. Flood coverage. Hurricane deductible. Dwelling limit. Exterior structures. Ordinance and law costs. Then the agent checks whether those pieces work together or leave you exposed.
That separation is the whole point.
If your roof opens up from wind and rain enters from above, one policy may respond. If storm surge or rising water pushes in from outside, that is a different claim path. If both happen, you need your coverage built correctly before hurricane season, not argued over after it.
Ask for clear answers to these questions:
- Does the flood policy fit the home, or is it capped too low for the property?
- Can you comfortably absorb the hurricane deductible without draining savings?
- Are the dock, pool enclosure, detached structures, and expensive exterior features treated properly?
- Do your policy limits reflect rebuild costs in Vero Beach, not just the last purchase price?
- If wind and flood hit in the same event, do you understand which carrier handles which part of the loss?
Local knowledge changes the advice. An older house on the island east of the bridge presents a different insurance problem than a newer home farther inland. Construction type, elevation, updates, shutters, roof age, and exact location all affect eligibility and claim risk. A quote pulled online rarely catches those details well.
That is why many waterfront owners choose to work with an independent insurance agent in Vero Beach FL who can compare options and explain the gaps in plain English. One local option is Professional Insurance Advisors, LLC, which works with home and flood insurance for this market.
My advice is simple. Do not buy waterfront insurance as if it is one policy solving one problem. It is a layered plan for a house exposed to two different kinds of hurricane loss. A good independent agent helps you set that plan up correctly before a storm turns a coverage gap into your money.
Frequently Asked Questions About Vero Beach Waterfront Insurance
Waterfront owners usually ask better questions after the first confusing quote. These are the ones I hear most often.
Quick answers that matter
If you're still uncertain, focus on the practical issue behind each question. Not the label on the policy. Not the marketing summary. Ultimately, the issue is who pays, when they pay, and what still comes out of your pocket.
| Question | Answer |
|---|---|
| Do I need flood insurance if I already have homeowners insurance? | If your concern is rising water, storm surge, or flood entering the home from outside, you need separate flood protection because standard homeowners coverage generally excludes flood. |
| Is all hurricane damage handled the same way? | No. Wind-related damage and flood-related damage can be treated under different policies, with different claim handling. |
| Should I choose the lowest premium available? | Not unless you've checked the hurricane deductible, exclusions, and endorsements. A lower premium can hide a larger out-of-pocket problem later. |
| Are island homes always harder to insure than mainland homes? | They often present tougher insurance questions because of coastal exposure, but the actual answer depends on construction, mitigation, age, and location specifics. |
| Does flood insurance always solve the whole problem for a high-value waterfront home? | Not automatically. You need to review whether the available flood structure coverage is enough for the home you own. |
| What should I keep on hand before storm season? | Your policy documents, agent and carrier contact information, property photos, a home inventory, and a plan for temporary repairs and claim reporting. |
The question I wish more owners asked
Ask this before you bind or renew coverage: "If a hurricane hits my home tonight, what exact type of damage would be handled by each policy, and what amount would I have to absorb first?"
That question cuts through almost every sales shortcut in this market. If the answer isn't clear, the coverage isn't ready.
If you own a home on the river, near the beach, or anywhere flood and wind can collide, get a policy review before the next storm forces the issue. Professional Insurance Advisors, LLC can help you compare the structure of your current coverage, identify flood and wind gaps, and sort out whether your deductibles and endorsements fit the home you own.