
Motorized RV coverage in Florida typically runs $1,000 to $2,000 a year, while towable RV coverage often falls between $200 and $600 a year. In Vero Beach, the key question is whether your policy holds up when a storm parks over the coast and your RV sits through hurricane season.
That gap is not random. It comes from vehicle type, usage, Florida minimums, and the ugly reality that coastal storage rules and named-storm conditions can create coverage gaps even when the premium looks fine on paper. If you own an RV here, you need more than a quick quote. You need a policy that survives a Florida storm season.
Table of Contents
- What RV Owners in Vero Beach Are Really Paying
- The Core Coverage Types Every Vero Beach RV Needs
- Florida Minimums and Vero Beach Storm Risks
- What Actually Moves Your RV Insurance Price
- Sample Premium Ranges and Discounts That Lower Them
- How to Get an Accurate Quote in Vero Beach
- Common Exclusions and the Endorsements That Close the Gaps
- Filing an RV Claim After a Vero Beach Storm
What RV Owners in Vero Beach Are Really Paying
A Vero Beach owner with an RV parked through storm season does not care about marketing copy. The question is what the policy costs, what it leaves exposed, and whether the quote still makes sense after you add the coverages that matter here. For a motorized RV, Florida pricing often lands around $1,000 to $2,000 a year. Towable rigs usually run $200 to $600 a year. Those ranges reflect the market and the weather risk built into Florida rates.
Why the range widens here
Industry data shows Florida averages for RV coverage sit above the national norm, with travel trailers and motorhomes both costing more here than in many other states (Florida RV insurance guide). That gap is not random. Coastal exposure, storage setup, and how often the RV moves all push the price around in Vero Beach.
A quote that looks cheap online can miss the parts that matter after a storm. That usually means weak physical damage coverage, no protection for stored equipment, or a deductible that looks fine until the first roof claim. The smartest way to price an RV policy here is to compare the base RV premium with the cost of bundling Home and Auto through a local independent agency, because that is where many owners see the practical difference. Motor Sportsland on RV coverage is a useful reminder of the common coverage buckets, but local storm exposure still drives the decision.
If you want a cleaner quote, use an agency that can place the RV with your home and auto instead of pricing each line in a vacuum. Professional Insurance Advisors, LLC motorhome insurance guidance is the kind of local reference point that helps owners see where the gaps are before hurricane season tests them. The quote that survives Vero Beach is the one that accounts for storage, storm exposure, and the way the policy responds when the RV sits still for months.
The Core Coverage Types Every Vero Beach RV Needs
A strong RV policy needs layered protection, because a Vero Beach RV faces different problems on the road, at the storage lot, and during hurricane season. Liability handles what you do to other people, collision and other coverage protect the rig itself, and roadside assistance keeps a breakdown from turning into a bigger problem. If one part is missing, the policy may still look complete, but the loss that matters most can land on you.

The six pieces that matter
Bodily injury liability pays when you hurt someone in a crash. Property damage liability pays when you damage another person's vehicle or property. For a motorhome, Florida treats these as required protections before registration, while a travel trailer or fifth wheel is handled differently under state law. If you want a straight read on how that applies to a specific rig, start with motorhome insurance guidance from Professional Insurance Advisors, LLC.
Collision pays for damage to your RV after a crash, whether you hit a guardrail, a curb, or another vehicle. Other-than-collision is the storm and non-crash layer, the one that matters when a tree falls, hail dents the roof, or theft takes the contents. Uninsured and underinsured motorist coverage steps in when the other driver has too little insurance to cover your injuries.
Medical payments can help with injury-related medical costs after an accident, depending on the policy. Emergency roadside assistance covers the tow, tire change, and lockout that can stop a small breakdown from eating up your day. Vacation liability matters more for towables and parked rigs, because it can protect you when the RV is being used as temporary living space.
Practical rule: if you are paying for an RV and not insuring the interior, the gear, or the time you spend inside it, you are leaving the most expensive part of the risk exposed.
For a motorized unit, Florida minimums apply to registration and road use. For a towable unit, those legal minimums are not the same, but physical damage coverage still makes sense for most owners because the rig itself is the asset. The fine print on no-fault rules is where motorhomes and travel trailers start to diverge, and that is where many owners get surprised.
Florida Minimums and Vero Beach Storm Risks
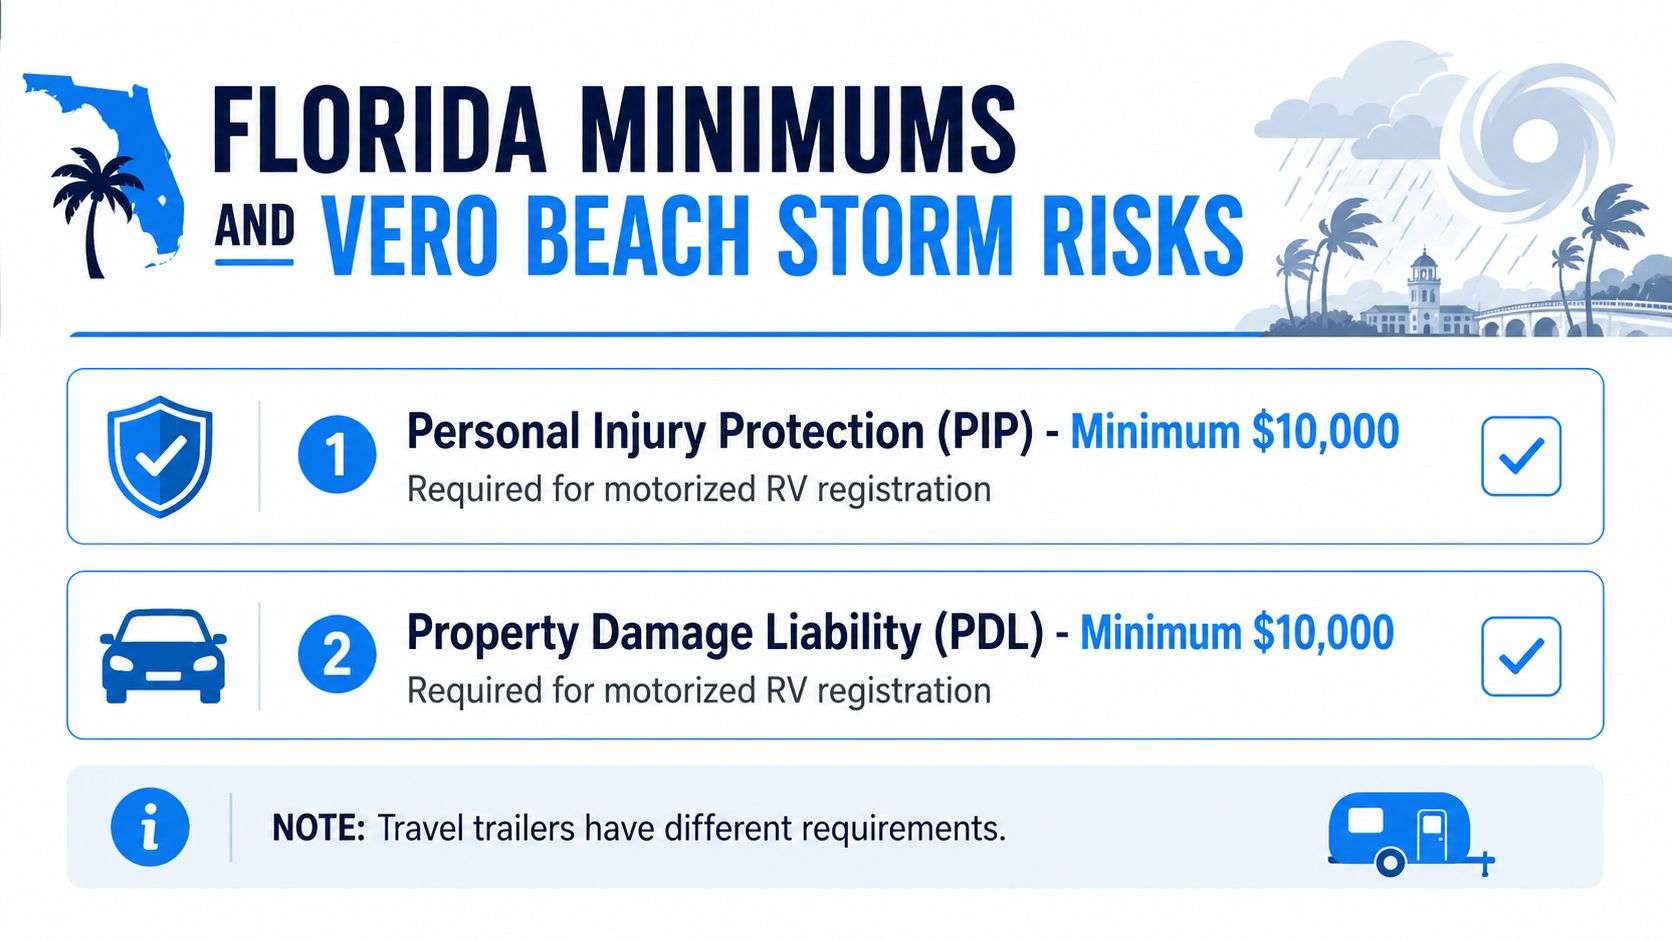
Florida does not let a motorhome hit the road without meeting the state's minimum auto-style requirements. Motorized RVs need at least $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL) before registration, because the state treats them like other self-powered vehicles in the no-fault system. Travel trailers and fifth wheels are not legally required to carry liability insurance, even though most owners still buy physical damage coverage to protect the rig itself.
Why the legal minimum is not the real standard
The minimum gets you registered. It does not get you through hurricane season with confidence. In Vero Beach, insurers warn that hurricane-season storage and wind-deductible conditions can affect whether coverage applies, and that matters in a market where the owner-occupied housing rate is 64.4% and the median owner-occupied home value is $392,500 (Vero Beach local risk context). When a household is protecting a high-value home and an RV at the same time, the policy has to fit the whole risk picture.
If your RV is parked near the coast and your policy expects inland storage or specific storm-placement rules, do not assume a claim will work just because the rig was sitting still.
That is the trap. Owners often think a parked RV is automatically safer and therefore fully covered. In reality, storage location, named-storm procedures, and deductible terms can decide whether the claim is paid or pushed back. That is why I tell clients to think about where the RV will sit during hurricane season before they buy the policy, not after the first storm watch.
If you are comparing RV coverage against a broader coastal protection plan, the Vero Beach flood insurance guidance is worth reading alongside your RV policy review. One policy protects the vehicle, the other protects the property exposure around it. In Florida, those two risks collide more often than people want to admit.
What Actually Moves Your RV Insurance Price
The make and model matter, but they do not control the whole bill. Vehicle class, usage pattern, storage location, and whether the RV is financed usually move the price more than owners expect. A Class A coach used by a snowbird will not price the same way as a travel trailer that sits in storage for most of the year.
The factors that change the quote
A motorized RV usually costs more to insure than a towable one because it combines vehicle coverage and living-space risk. A newer or more valuable unit often needs more protection because the insurer is looking at replacement cost and repair severity, not just the sticker. A clean driving record helps, while accident history and violations pull the number upward.
A full-time RVer also prices differently from a part-time user. Someone who spends months on the road is exposing the rig more often, and a family that keeps a trailer in a local storage facility is making a different risk decision than a couple who drive every weekend. If the RV is financed, collision and full coverage are usually expected whether the owner wants them or not, because the lender wants the asset protected.
Usage is the lever most owners underestimate. A rig that moves less can still cost more if its storage plan, financing, or seasonal use creates a tighter underwriting review.
Storage matters here in a very practical way. In Vero Beach, local storage guidance says most residential zones do not permit long-term outdoor storage of RVs, boats, trailers, or commercial vehicles, and storage facilities commonly ask for proof of insurance and title before acceptance (Vero Beach storage rules). That means your insurance file is not just a claims document. It is part of how you store the rig legally and practically.
Two RVs of the same year and class can land at very different prices because these factors stack. That is the part online quotes often flatten out, and it is why local review beats guessing.
Sample Premium Ranges and Discounts That Lower Them
A quote that looks low on the screen can still be overpriced for what it covers. In Florida, RV pricing often lands above national averages, and that gap gets wider once storm exposure, storage questions, and the type of rig all get factored in. Owners in Vero Beach should judge the number against the actual risk on the policy, not against a polished online estimate.
Sample Annual RV Premium Ranges in Florida
| RV Class | National Average | Florida Average | Vero Beach Range |
|---|---|---|---|
| Travel trailer | $594 | $841.16 | Roughly within towable market ranges |
| Motorhome | $1,052 | $1,386.04 | Roughly within motorized market ranges |
| Full-time motorhome | Not provided | Often $1,000 to $2,000 annually | Higher end of the market |
The row for full-time motorhome coverage reflects the broader industry estimate that full-time motorhome coverage often runs $1,000 to $2,000 annually. That is a planning range, not a promise, and it fits owners who live in the rig or put heavy miles on it.
Discounts That Significantly Reduce Premiums
Bundling Home and Auto can change the price because an independent agency can place the RV with one carrier while also reviewing the home and auto policies at the same time. That matters in Vero Beach, where the best household savings often come from the full package, not from the RV policy alone. The home and auto bundle discounts in Vero Beach discussion is worth having with a local advisor because it can expose savings that a standalone online RV quote will miss, especially when the same agency is also looking at flood and home coverage.
Other discounts are straightforward and worth asking for. Paying annually, completing an RV safety course, adding anti-theft devices, and choosing paperless billing can reduce cost when the carrier recognizes them. Those discounts help, but they do not fix weak coverage. A lower premium is a bad deal if the policy still leaves the roof, storage setup, or storm damage exposed.
How to Get an Accurate Quote in Vero Beach
Start with the paperwork, not the price. Bring the VIN, year, make, model, and current odometer reading so the carrier can identify the rig correctly. If you skip that part, the quote may look fine and still be wrong.
A clean quote process saves time later
Next, gather driver information for every household member who might drive the RV, plus any completed RV safety course certificates. That matters because the carrier is pricing the people as much as the vehicle. Then pull together proof of insurance, title, and any lien information, because local storage facilities commonly require those documents before they will accept the RV (Vero Beach storage rules).
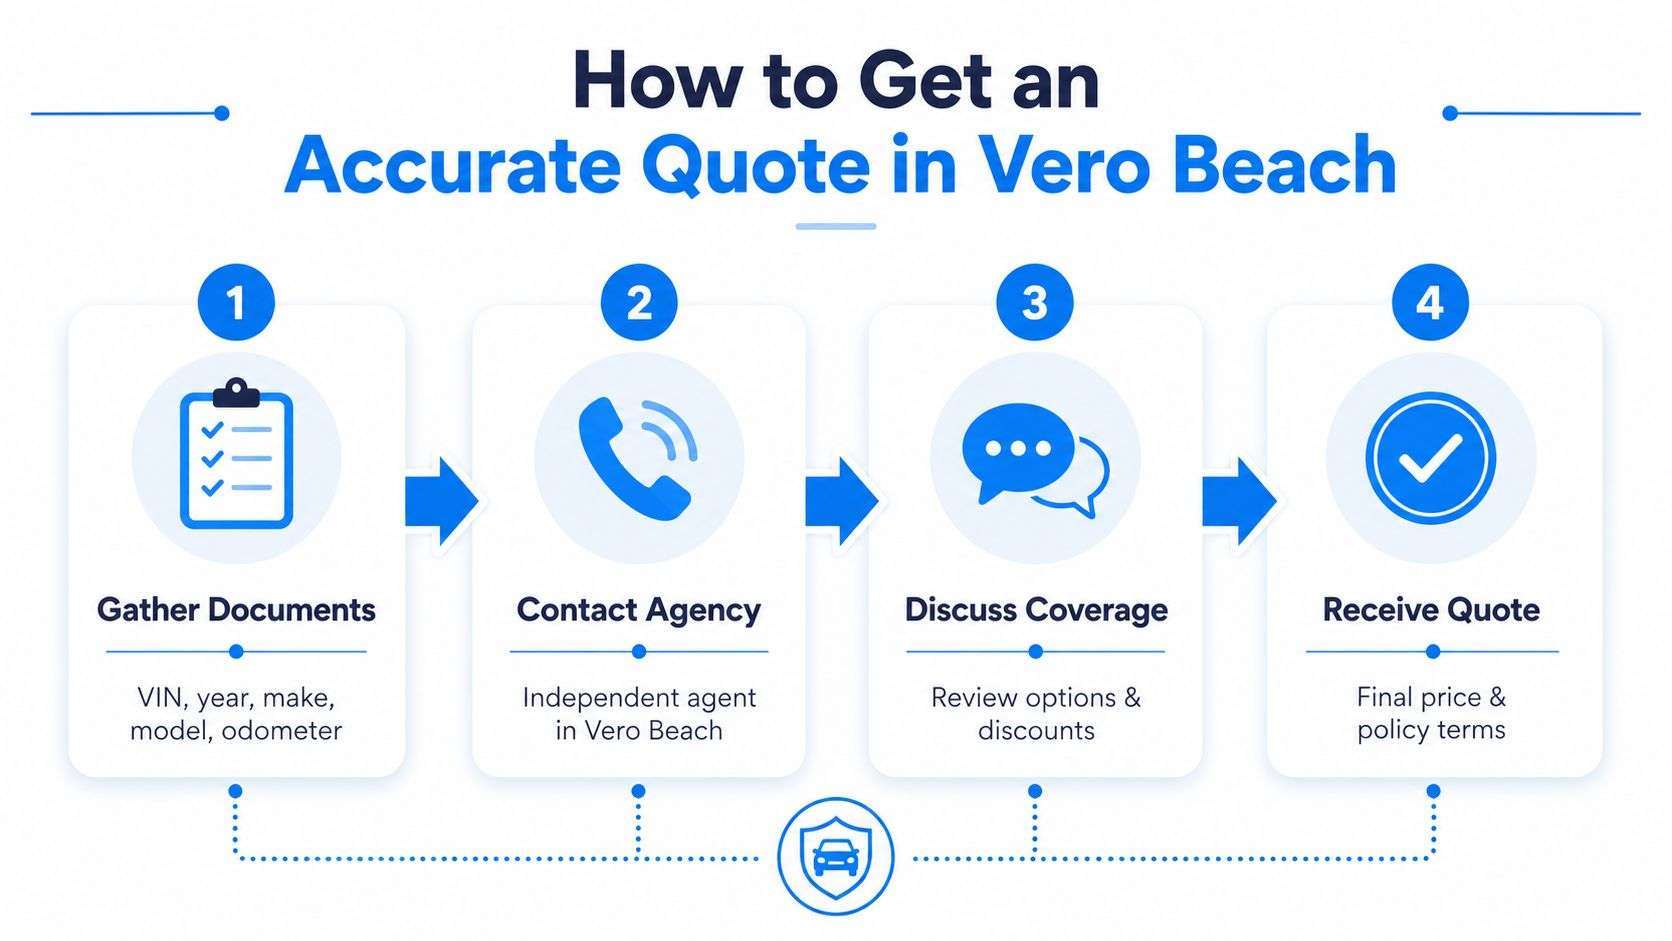
Then ask an independent agency to compare quotes from multiple carriers side by side. That keeps you from buying the first policy that sounds reasonable. Review the declarations page line by line, with special attention to deductibles, named-storm terms, and whether the policy covers personal belongings stored in the RV.
Keep this checklist ready
- VIN and rig details: Year, make, model, and odometer.
- Driver list: Everyone who may operate the RV.
- Safety proof: Any RV course certificate you completed.
- Ownership documents: Title and lien details.
- Storage documents: Proof of insurance for the facility.
If you want a local office to handle the quote comparison and document review, Professional Insurance Advisors, LLC can do that as part of its RV and household coverage work in Vero Beach. Use the quote review to compare the policy terms, not just the premium number.
Common Exclusions and the Endorsements That Close the Gaps
The exclusions that catch owners off guard are usually the boring ones. Wear and tear, mechanical or electrical breakdown, rodent damage inside the coach, off-road or uninsured driver incidents, commercial use, and damage from racing or reckless operation can all leave a claim in trouble if the loss does not fit the policy. Those are not weird edge cases. They are ordinary reasons a claim gets trimmed or denied.
Endorsements that make the policy more useful
A personal effects endorsement raises the protection for stolen or damaged belongings inside the RV. That matters when the TV, bedding, electronics, or kitchen gear are part of the loss. A pet injury endorsement gives you some coverage for a travel dog or cat, which is more relevant for full-time and extended-trip owners than many realize.
Full-timer coverage turns an RV policy into something closer to a homeowners-style structure for people who live in the rig year-round. Emergency vacation expense coverage can help pay for hotels and travel if the RV becomes uninhabitable after a covered loss. Those are not luxury add-ons. They are the difference between a nuisance and a major interruption.
Exclusions are decision points. The right endorsement does not make the policy fancy, it makes it usable.
The mistake I see too often is assuming the base policy is enough because the RV is parked most of the year. Parking does not erase wear, theft risk, or storm exposure. The endorsement review is where you close the gap before a loss, not after the adjuster explains what was left out.
Filing an RV Claim After a Vero Beach Storm
The first move after a named storm is safety, not paperwork. Get people clear, make sure the RV and the area around it are safe, then take photos and video before you move anything. Once the scene is documented, call your insurance advisor, not just the 800 number, because a local agent can help sort out the coverage details in plain English.
What the claim process usually looks like
File the claim promptly and keep every receipt tied to the loss. Temporary lodging, towing, and emergency repairs can become part of the reimbursement discussion under loss-of-use or emergency expense provisions, depending on the policy language. The adjuster will inspect the damage, compare the repair estimate to the policy terms, and decide what falls inside coverage.
If the estimate comes in too low, push back with documentation. A second repair quote, photos, and comparable parts or labor information can support your case better than an emotional argument ever will. That is especially true after storm losses, when shops are busy and materials are scarce.
Keep your documentation boring and complete. Boring wins claims.
One Vero Beach-specific issue matters more than people expect. If the RV was stored inland during the storm and the policy required it, that documentation can be the difference between a paid claim and a denied one. The storage decision is not just about protecting the rig from wind. It is about meeting the exact terms you agreed to.
That is why local, independent help matters. A Florida-based agency serving clients since 1985, with 120 years of combined staff experience, can quote multiple carriers, review bundling with home and auto, and pair RV coverage with a competitive flood policy when the household needs it most. The agency's value is not a slogan, it is having someone who knows the policy language before the storm and the claim process after it.
Professional Insurance Advisors, LLC helps Vero Beach RV owners compare coverage, bundle home and auto, and line up flood protection with the RV policy so the whole household risk gets handled together. If you want a straight quote review and a local advisor who will explain the tradeoffs before hurricane season tightens up, visit Professional Insurance Advisors, LLC and start the conversation today.