
In 2025, Florida's average annual homeowners insurance cost reached $8,292, and flood damage is excluded from a standard homeowners policy. That means Roseland owners need to budget for expensive wind coverage while making a separate decision about flood protection.
A renewal notice can make that reality feel personal. You may live in a well-maintained home, have never filed a claim, and still see a sharply different premium because insurers evaluate roof age, rebuild cost, storm exposure, and their appetite for Florida property. The right response isn't to accept the cheapest quote automatically or drop important coverage. It's to read the policy line by line and separate three decisions, structural protection, hurricane wind risk, and flood exposure.
Table of Contents
- What Roseland Homeowners Are Up Against in 2026
- What a Standard Homeowners Policy Actually Covers
- Wind, Hurricanes, and the All-or-Nothing Mitigation Credit
- Hurricane Deductibles and How to Choose Yours
- Why Flood Coverage Is a Separate Decision
- What Drives the Price of Roseland Home Insurance
- How to Compare Quotes and Pick the Right Carrier
- Lowering Your Risk and Your Premium Next Year
What Roseland Homeowners Are Up Against in 2026
A Roseland homeowner opens a renewal notice and sees a 22% premium increase. The roof is maintained, the mortgage is current, and there has been no claim. The homeowner must decide whether to stay with the carrier, shop the policy, or reduce coverage and accept more risk.
That decision sits inside Florida's statewide insurance market. Statewide underwriting changes can affect a small Indian River County community, even when the home's condition has not changed. Review Indian River County insurance guidance for local context, then read your own quote line by line instead of treating a statewide average as a personal offer.
Florida's insurance costs remain high, but published averages do not describe every Roseland property. One statewide premium measure reported an average annual cost of $8,292 in 2025, compared with a national average of $2,580. Another statewide measure placed the average around $3,023. The gap between those figures proves the point: methodology, coverage limits, property characteristics, and location can change the result. Use averages to understand market pressure, not to predict your renewal.
Statewide rate changes also moderated from 9.6% in 2023 to 1.3% in 2024 and 0.9% in 2025, while Florida remained the country's most expensive home insurance state in 2025. The Insurance Journal's Florida market coverage reports these market figures. They explain the broader pressure, not the price of your specific home.
Why a Roseland quote can diverge from the headline
Reinsurance costs, carrier withdrawals, roof-age scrutiny, litigation history, hurricane exposure, and changes in Citizens participation affect availability and pricing. A private insurer may offer a different premium, deductible, inspection requirement, or coverage restriction than the policyholder expects.
Read four items first: the dwelling limit, wind coverage and exclusions, hurricane deductible, and flood arrangement. A low premium can reflect a lower rebuild limit or more risk assigned to you. Check whether the quote includes replacement-cost treatment, ordinance-or-law coverage, personal property limits, and additional living expense coverage.
Flood requires its own buying decision. Standard homeowners insurance does not cover flood damage, and wind coverage does not replace flood coverage. A storm can produce both wind and rising water, but the policy response depends on which peril caused the loss and what coverage you purchased.
| Quote item | What to check |
|---|---|
| Dwelling limit | Is it enough to rebuild the home? |
| Wind coverage | Are exclusions, limits, and inspections acceptable? |
| Hurricane deductible | Can you fund it after a major storm? |
| Flood protection | Is separate coverage appropriate for the property? |
For a Roseland owner, the recommendation is direct: compare the full policy, not just the premium. Keep adequate dwelling coverage, choose a deductible you can pay, and evaluate flood protection separately from hurricane wind insurance.
What a Standard Homeowners Policy Actually Covers
An HO-3 policy is easier to understand when you treat the declarations page like a household budget. Each coverage line pays for a different category, and a low premium can hide a lower limit or a larger share of the risk assigned to you.
Start with the structure
Coverage A, dwelling, is the amount available to rebuild the home after a covered loss. It should track replacement cost, not the home's sale price or land value. Florida coastal coverage guidance recommends insuring the home at 100% of replacement cost value, because coinsurance penalties can apply below the required threshold. A 1,800-square-foot concrete block home in Roseland may have a rebuild cost that differs substantially from its market value because labor, materials, demolition, and code upgrades are priced separately.
Coverage B, other structures, commonly applies to detached structures such as a shed, fence, or detached garage. The plan structure often sets this at 10% of the dwelling limit, but you should confirm the actual declarations page rather than assume the default applies.
Coverage C, personal property, commonly uses 50% of the dwelling limit as a starting limit. Replacement-cost personal property coverage pays to replace eligible belongings, while actual-cash-value treatment subtracts depreciation. That distinction matters after a loss because used furniture, electronics, and appliances may be worth much less at claim time than the cost of buying them new.
Coverage D, loss of use, commonly uses 20% of the dwelling limit for additional living expenses when a covered loss makes the home unlivable. Personal liability protects against covered claims involving injury or property damage to others, while medical payments can address eligible minor injuries without requiring the same liability determination.

Know what the policy leaves out
The main dwelling usually receives broader open-perils treatment, meaning the policy covers direct physical loss unless the policy excludes it. Other structures and personal property commonly receive named-perils treatment, meaning the cause of loss must appear on the policy's list.
Typical exclusions include flood, earth movement, wear and tear, business use, and pest damage. Ordinance or Law coverage can help with code-required rebuilding costs, while water backup coverage addresses a different water-loss scenario from flood. Both are optional endorsements that deserve a deliberate review. If you're checking exterior damage before a renewal inspection, this reference on residential roof hail damage can help you identify issues to discuss with your agent.
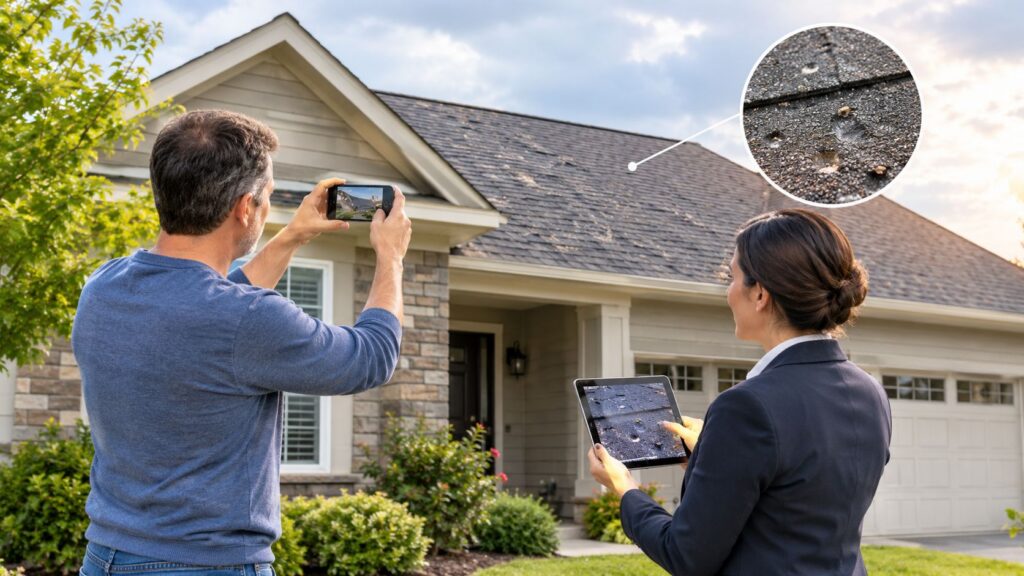
Before comparing a new quote, write down Coverage A through Coverage D, personal property valuation, liability limits, deductibles, endorsements, and exclusions. Compare those lines, not just the premium at the bottom.
Wind, Hurricanes, and the All-or-Nothing Mitigation Credit
A newer roof does not automatically earn a wind discount. Insurers look for documented construction features on an approved mitigation inspection form, including roof-deck attachment, roof shape, secondary water resistance, opening protection, and compliance with high-wind construction standards.
Roseland homeowners most often lose credit at the openings. Every glazed and exterior opening needs approved shutters or impact-rated glazing for the applicable opening-protection credit. One unprotected window, skylight, or glazed garage-door panel can remove that credit, even when the rest of the house is fortified. Review the Florida wind-mitigation form guidance before scheduling the inspection so you understand what the form documents.

Treat the inspection as an underwriting document
A mitigation inspection changes the wind portion of the policy, not every part of the premium. The reduction depends on the carrier, the home's construction, its location in Indian River County, and the features documented in the report. Older coastal properties may also prompt discussion of wind-only coverage, although availability has narrowed.
Do not assume the insurer has current records. You may have installed shutters, replaced a garage door, or reinforced the roof without sending proof to the carrier. Until the documentation is accepted, the quote may be rated as if the improvement does not exist.
Read the quote line by line. Confirm the wind premium, mitigation credits, inspection date, and deductible separately from the total price.
Practical rule: If one opening remains exposed, ask whether the carrier will apply any credit before treating the projected savings as real.
Before renewal, arrange a current mitigation inspection and complete an opening inventory. Check every window, exterior door, skylight, and garage-door section. Then compare the report with the home's actual condition and verify that the carrier entered every eligible wind credit. A statewide average can hide this Roseland-specific difference, so your documented features matter more than a headline premium.
Hurricane Deductibles and How to Choose Yours
A hurricane deductible can turn a manageable repair into a major cash problem. It is usually calculated against the policy's dwelling limit, not the repair invoice. Florida homeowners policies must offer $500, 2%, 5%, and 10% deductible choices, unless a percentage amount would be less than $500, according to the Florida Chief Financial Officer's hurricane deductible guidance.
Read the quote using the dwelling limit shown on your own policy. For a $300,000 dwelling limit, the percentage choices mean $6,000, $15,000, or $30,000 out of pocket. For a $450,000 limit, they mean $9,000, $22,500, or $45,000. The $500 choice remains a flat deductible when available.
Homes with dwelling limits from $100,000 to $249,999 can fall under a statutory alternative. The insurer may guarantee one renewal period and offer a hurricane deductible of up to 2%, rather than offering the $500 option. The Florida statute on hurricane deductibles describes that mechanism.
Florida defines the hurricane deductible period as starting when a hurricane warning is issued for any part of the state and ending 72 hours after the last hurricane watch or warning is lifted. Wind damage during that period can therefore use the hurricane deductible instead of the all-other-perils deductible.
| Deductible Option | Out-of-Pocket at $300K Dwelling | Out-of-Pocket at $450K Dwelling | Typical Annual Premium Impact |
|---|---|---|---|
| $500 | $500 | $500 | Usually higher than percentage options |
| 2% | $6,000 | $9,000 | Usually lower than $500 option |
| 5% | $15,000 | $22,500 | Usually lower than 2% option |
| 10% | $30,000 | $45,000 | Usually lowest among listed options |
Choose from cash reserves, not the premium alone. If a percentage deductible would force you to borrow after a storm, the savings are not worth the exposure. Ask for the same Roseland coverage quoted with every available option, then compare the deductible, wind premium, dwelling limit, and total annual cost line by line. Statewide averages can hide this trade-off. Your own reserve and home value should set the choice.
Why Flood Coverage Is a Separate Decision
A standard HO-3 policy doesn't cover flood damage. Florida law treats flood as separate coverage, so a homeowner must obtain a stand-alone policy through the National Flood Insurance Program or a private flood insurer, as explained in this guide to whether flood insurance is required in Florida.
Flood isn't limited to a home beside open water. Storm surge, heavy rainfall, drainage failure, and canal overflow can affect properties with different elevations and flood-zone classifications. A lender may require flood coverage based on its own underwriting rules, but the absence of a lender requirement doesn't mean the exposure has disappeared.
Compare the policy forms, not just the price
An NFIP policy offers building and contents coverage subject to program limits. The infographic identifies $250,000 for the dwelling and $100,000 for contents. Private flood policies may use different limits and can offer features such as higher limits, replacement-cost treatment for contents, and loss-of-use coverage, depending on the policy.
New flood policies can also have a 30-day waiting period, so buying after a storm is approaching may not solve the immediate problem. Ask about waiting-period exceptions, contents valuation, temporary living expenses, foundation coverage, and exclusions for below-grade areas.
Florida's market is moving toward broader flood requirements for wind-bearing residential policies by 2027, according to the cited Florida Hurricane Catastrophe Fund presentation. That projected regulatory shift reinforces the practical point. Treat flood as a primary buying decision now, not as paperwork to handle after a wind quote is finalized.
What Drives the Price of Roseland Home Insurance
Your rebuild limit is the foundation of the quote. Insurers need an estimate of what it would cost to reconstruct the home, including materials, labor, debris removal, and code-required upgrades. Market value is a poor substitute because it includes land and reflects buyer demand rather than construction expense.
Florida carriers then examine the roof closely. Age, material, shape, attachment, remaining useful life, and inspection results can affect eligibility and price. A roof that looks acceptable from the driveway may still produce underwriting questions if records are missing or the carrier believes its remaining life is limited.
The rating factors that deserve your attention
- Claims history: Prior property claims can affect eligibility and pricing. Ask how the carrier evaluates recent loss history before assuming a claims-free discount applies.
- Credit-based insurance score: Where permitted, the insurer may use credit-related information as one rating input. Improving payment habits can help over time, but the agent should explain how the carrier uses the factor.
- Protective features: Impact-rated shutters, reinforced garage doors, monitored alarm systems, smoke detectors, water-leak sensors, and automatic shutoff devices can affect risk evaluation.
- Location: Distance to the coast, fire protection quality, hydrant access, drainage, and prior wind-loss history can distinguish two homes that appear similar on a map.
- Policy bundling: Combining home and auto coverage can create savings opportunities, while an umbrella policy can address higher liability needs. The bundle should still be compared on matching limits and deductibles.

Why statewide averages mislead
The statewide figures described earlier combine homes with different construction, geography, roof condition, limits, claims, and carrier classifications. A Roseland quote may run above or below the headline average for reasons specific to the property, not because the agent priced it incorrectly.
The cheapest quote is only cheaper if it protects the same home, with the same deductibles, exclusions, and rebuild assumptions.
Ask for the replacement-cost worksheet and challenge any dwelling limit that doesn't reflect current rebuilding conditions. Underinsurance can save premium today while leaving a serious gap after a covered loss.
How to Compare Quotes and Pick the Right Carrier
Start before contacting an agent. Gather the home's square footage, year built, roof age and material, construction type, opening protection, mitigation features, claims history, mortgage information, and the dwelling limit you want to protect. Missing facts often lead to conservative assumptions, delayed underwriting, or a quote that changes after inspection.
Use a consistent quoting workflow
- Prepare the property file. Collect roof invoices, permits, mitigation reports, shutter or impact-window documentation, alarm details, and photos of major updates.
- Request several options. Ask for quotes from carriers actively writing homes in Indian River County. Online instant tools can miss credits that depend on an approved wind-mitigation form or carrier-specific underwriting.
- Keep the coverage identical. Use the same Coverage A limit, contents valuation, liability limit, hurricane deductible, water-backup limit, ordinance coverage, and flood assumptions.
- Ask for re-underwriting. Bind through an agent who can review inspection results and supporting documents instead of treating the initial automated quote as final.
- Read the declarations page. Confirm every line before accepting the policy.
The declarations page should show Coverage A replacement cost, not a casual market-value estimate. Check the hurricane deductible percentage, any wind exclusion or wind-only structure, Ordinance or Law coverage, water-backup limit, personal-property valuation, and mold caps. A low premium may shift risk through a lower dwelling limit, a higher deductible, narrower coverage, or a property class the carrier may not renew.
A Florida homeowners insurance comparison guide can help organize the questions, but your own declarations page remains the controlling document.
| Field | Carrier A | Carrier B | Carrier C |
|---|---|---|---|
| Coverage A rebuild limit | |||
| Personal property valuation | |||
| Hurricane deductible | |||
| Wind exclusion or limitation | |||
| Ordinance or Law coverage | |||
| Water backup limit | |||
| Mold limitation | |||
| Renewal and inspection conditions |
Ask each carrier how it handles Florida claims, whether assignments of benefits create restrictions, and how recent rate filings or underwriting changes may affect renewal. Professional Insurance Advisors, LLC can compare coverage from available carriers and review flood, mitigation documentation, deductibles, and storm-related gaps as part of that process.
Lowering Your Risk and Your Premium Next Year
Use the next renewal cycle as a project, not a surprise. The most useful improvements are the ones that both reduce physical damage and give the insurer evidence it can rate.
A practical 12-month checklist
- Schedule a current wind-mitigation inspection: Confirm roof attachment, secondary water resistance, roof shape, and complete opening protection.
- Close every opening gap: Upgrade shutters, impact-rated windows, and glazed garage-door panels so one unprotected opening doesn't undermine the credit.
- Review the roof plan: Replace an aging roof when appropriate and discuss high-wind-rated materials with the contractor and agent before work begins.
- Install protective systems: Consider monitored alarms, smoke detectors, water-leak sensors, and smart shutoff valves where they fit the home.
- Remove preventable hazards: Secure loose outdoor items, address dangerous trees, and remove or properly protect features that increase injury exposure.
- Recheck limits annually: Update the dwelling limit after renovations, material-cost changes, additions, or code upgrades.
- Review claims carefully: Don't use insurance as a maintenance account. Ask about the consequences of a small claim before filing one.
- Requote the bundle: Compare home and auto together, then review whether umbrella liability remains appropriate.
Roseland coverage questions homeowners still ask
Do I need flood insurance if my lender doesn't require it? The lender's decision doesn't change the HO-3 exclusion. Flood remains a separate risk, and rainfall, surge, and overflow can affect homes outside the areas owners commonly associate with flooding.
Should I choose a 2%, 5%, or 10% hurricane deductible? Choose the highest deductible you can pay without financial distress. A lower premium isn't a savings if the post-storm bill would force you into debt.
Does a newer roof guarantee a lower premium? No. The carrier still evaluates construction, documentation, mitigation, claims, location, and the policy's overall terms. A new roof can improve underwriting, but it doesn't erase every rating factor.
Mitigation investments compound. They can reduce storm damage, support a more accurate quote, improve the quality of your documentation, and give you stronger negotiating position if a carrier changes its appetite or sends a non-renewal notice.
Professional Insurance Advisors, LLC helps Roseland homeowners compare home, wind, flood, and bundled Home and Auto options while reviewing deductibles, mitigation records, rebuild limits, and storm-related gaps. Visit Professional Insurance Advisors, LLC to start a coverage review and request guidance built around your property's actual risks.