
You sign the lease, move your boxes into a Vero Beach apartment, and assume the insurance problem is handled. Then a storm rolls through, water gets where it should not, and the first question is the one most renters ask too late, what pays for the loss? In coastal Florida, Renters Insurance Vero Beach is not a paperwork formality, it is the policy that keeps a theft, fire, or liability claim from turning into a personal financial mess. The mistake is thinking a lease-required policy automatically covers every storm loss, because it does not.
Florida renters need a policy that fits coastal exposure, not a generic out-of-state template. Standard renters insurance is built around personal property, liability, and additional living expenses, but the flood gap changes everything in a place like Vero Beach. If you are comparing options, it helps to understand why the landlord's building coverage is not your coverage, and why a renter should still read guidance meant for property owners, such as insurance for rental property owners from Edinhart Realty and Property Management, before assuming any policy fills every hole.
Table of Contents
- Why Vero Beach Renters Need More Than Basic Coverage
- What Renters Insurance Actually Covers in Florida
- The Flood and Windstorm Coverage Gap Every Renter Should Know
- How Much Renters Insurance Costs in Vero Beach
- Discounts and Bundling Strategies to Lower Your Premium
- How to Build a Home Inventory and File a Claim Successfully
- Getting a Personalized Quote from a Vero Beach Insurance Advisor
Why Vero Beach Renters Need More Than Basic Coverage
A renter in Vero Beach can do everything right, pay on time, keep valuables inside, and still get blindsided after a storm. The hard truth is that a standard renters policy is not built to absorb every coastal loss, and the gap usually shows up after the damage is already done. Nationally, about 55% of U.S. renters, or roughly 61 million people, have renters insurance, while 45% remain uninsured according to the Insurance Information Institute, and that uninsured slice is where a lot of avoidable financial pain lives. Insurance Information Institute renters insurance facts
For a Vero Beach renter, the core issue is not whether coverage exists, it is whether the policy matches the risk. Standard renters insurance generally protects personal property, liability, and additional living expenses, but it does not include flood damage. That means you can have a policy in place and still be exposed if storm surge or rising water gets into the rental.
Practical rule: if the damage comes from rising water, do not assume the renters policy is enough.
The market reality makes this worse. Florida has had tighter underwriting and more confusion around what is covered, which is why renters need to read their policy with a sharper eye than they would in a low-risk inland market. A lease can require proof of renters coverage, but that does not make it a complete coastal-loss solution. The smartest move is to treat the policy as a baseline, then verify whether you need separate flood protection or another layer for the risk that the base policy leaves out.
What Renters Insurance Actually Covers in Florida

A Florida renters policy comes down to three moving parts. It protects your belongings, covers certain liability claims, and can pay temporary living costs after a covered loss makes your place unlivable. The Florida CFO's renters guide describes renters insurance as a named-peril, contents-first contract, and that is the right way to read it. Florida CFO renters insurance toolkit
Personal property coverage
This is the part renters usually notice first. It can respond when your belongings are damaged by covered events like fire, theft, vandalism, or certain water damage, and it is the coverage that matters when furniture, electronics, clothes, or other household items need to be replaced. A burglary that empties a parked car or a kitchen fire that ruins your couch can fall under this section if the loss fits the policy terms.
Coverage limits deserve real attention. Florida policy structures often place personal property limits in the $20,000 to $30,000 range, and that may work for some renters while leaving others underinsured. If you own upgraded furniture, better electronics, or a lot of seasonal gear, the limit should match the cost to replace those items, not what you originally paid years ago.
Personal liability
Liability coverage matters the moment someone gets hurt or you accidentally damage another person's property. If a guest slips in your apartment or your dog bites a neighbor, this part of the policy is designed to defend you and pay covered claims, subject to the policy terms and limits. Florida consumer guidance also includes medical payments to others as part of the renters package, which can handle smaller injury claims without turning every incident into a larger liability fight.
Additional living expenses
This coverage pays when a covered loss forces you out of your rental. It can help with hotel costs, meals, and other temporary expenses while the unit is being repaired. That matters in Vero Beach, where a fire or another covered event can leave you displaced fast and scrambling for short-term housing.
One more reality check, renter obligations and insurance duties are separate. A practical overview like who pays for pest control in Miami helps show how lease responsibilities are handled, even though the insurance rules are different. For a Vero Beach renter, the bottom line is simple, renters insurance helps only when the loss is one the policy names. A flood exclusion still leaves a gap, and a tight policy limit still leaves you paying the difference.
The Flood and Windstorm Coverage Gap Every Renter Should Know
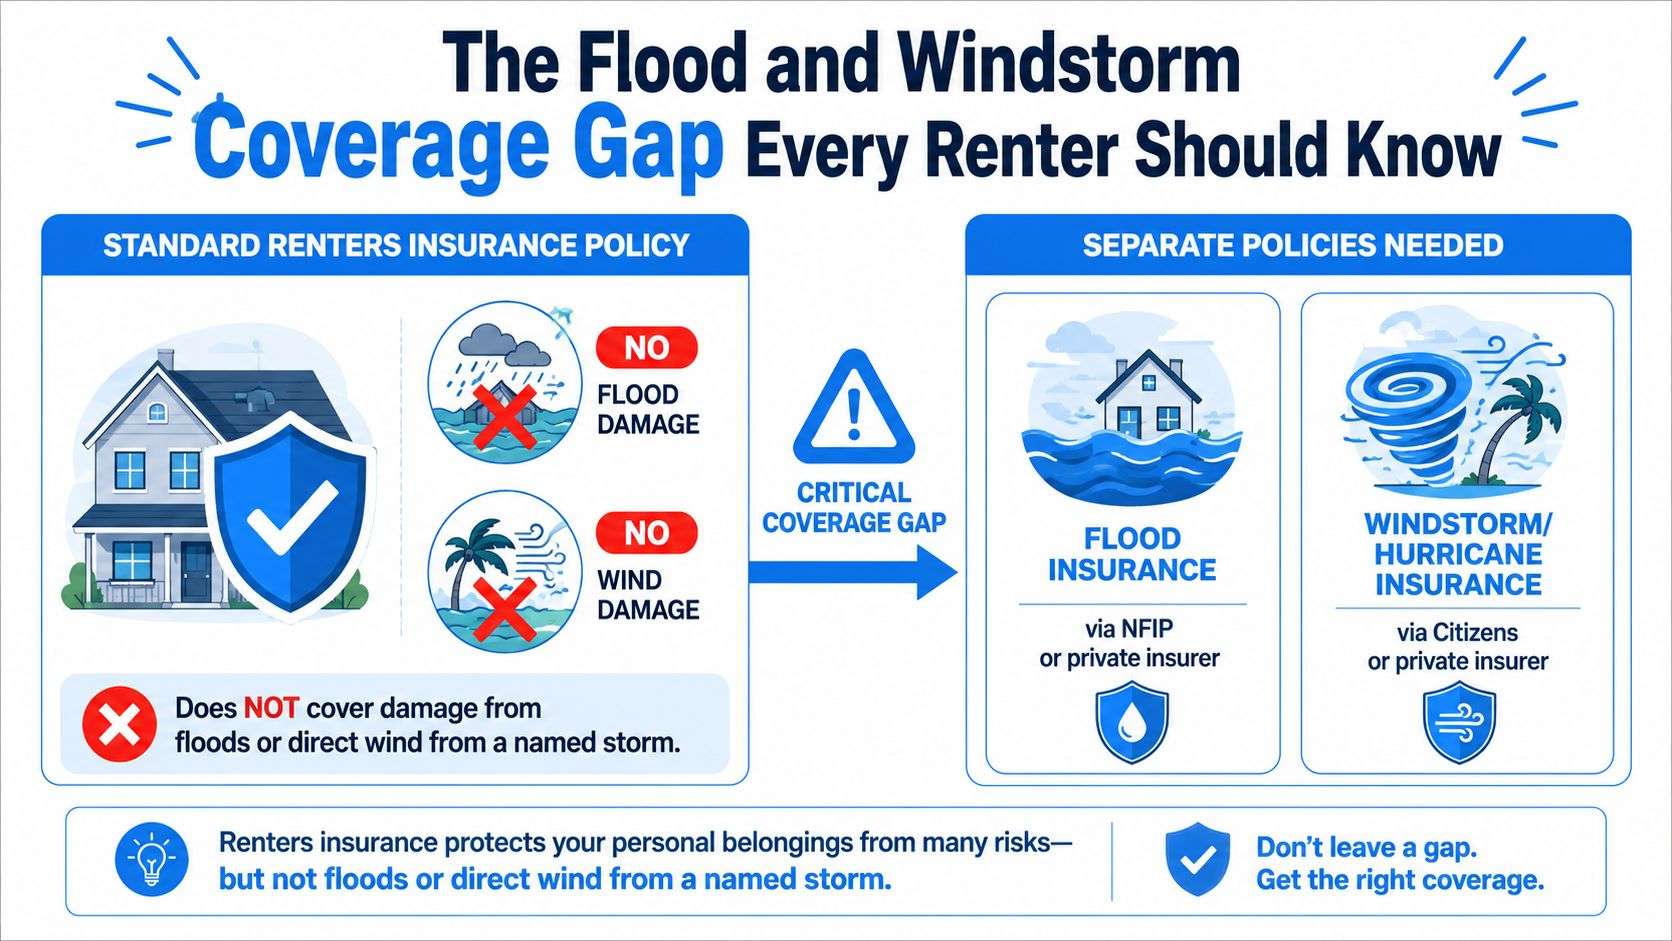
The biggest mistake renters make in coastal Florida is assuming storm damage is storm damage. It is not. A standard renters policy can respond to covered wind-related damage in some situations, but it still does not cover flood damage, including storm surge or rising water. Florida consumer guidance says this directly, and that distinction is the entire problem for coastal renters. Florida CFO renters insurance toolkit
Why the gap matters in Vero Beach
Vero Beach renters face a layered risk profile. You may have a lease-required renters policy in place, but that policy can still leave a hole where flood exposure lives. Florida regulators note that flood coverage may sometimes be added by endorsement, and if the insurer does not offer it for personal property, a separate flood policy is needed. That is why a renters policy should be treated as one layer, not the whole shield. Florida renters insurance guidance
A lease requirement is not a substitute for flood protection.
That is especially true in coastal counties where low elevation and storm surge can produce water damage even when the building itself survives the wind. If water comes up through the ground, pushes in under doors, or enters from flooding outside the unit, you are in the flood problem, not the ordinary renters claim problem. For a direct local overview of the flood issue, this Vero Beach flood insurance resource is worth reading because it focuses on the renter-specific gap, not just homeowners.
Windstorm deductibles and coverage layering
Florida renters also need to understand that premium price is only half the story. Some policies have different deductible structures, and a higher deductible can lower the price while leaving you with more out-of-pocket cost after a claim. The practical result is that two renters can pay different amounts and still have very different claim experiences.
Florida renters policies are usually part of a coverage layering problem, not a single-policy solution. You may need the base renters policy for your belongings and liability, then separate flood protection for rising water, and in some arrangements an added windstorm-related layer if available. A lease that says you must carry renters insurance is only telling you to have the minimum, not the complete answer for a hurricane-prone coastal rental.
How Much Renters Insurance Costs in Vero Beach
A Vero Beach renter can usually get basic renters insurance for a modest monthly price, but the quote is shaped by more than the size of the apartment. Coverage limits, deductible choices, location, construction, age of the residence, roof, plumbing, electrical, heater, air conditioner, and prior claims experience all affect what an insurer charges, and Florida regulators recognize those factors in premium setting. Florida renters insurance toolkit
The market numbers give you a realistic starting point. The Insurance Information Institute reported an average U.S. renters insurance premium of $171 in 2022. Florida-focused rate reviews have also shown state averages of $204 per year in one case and $152 per year in another, depending on carrier mix and coverage assumptions. Insurance Information Institute renters insurance facts, Florida renters rate comparison
What moves the price
A renter with modest belongings and a standard deductible usually pays less than someone insuring higher-value contents and choosing tighter claim terms. Coastal proximity matters too, because underwriters price water exposure and storm risk more carefully near the ocean. Florida's market pressure has made quote differences feel wider, so two renters in the same building can still see very different prices.
A few carrier examples help show the range. A basic Florida renters policy with $20,000 in personal property coverage and $100,000 in liability can land around $15 to $25 a month, while a higher coverage example with $30,000 in personal property and $100,000 in liability can sit around $18 a month. Those figures come from Florida market examples, not guarantees. Florida renters pricing examples
A Vero Beach renter should expect a manageable monthly bill for baseline protection, then adjust the policy to match what is inside the rental and how much risk the location creates. If a quote looks too high, inspect the deductible first, then the amount of personal property coverage, then any gap between the lease requirement and the protection you need. If you are comparing a renters and auto package, start with home and auto bundle discounts in Vero Beach before you cut coverage just to chase a lower premium.
Discounts and Bundling Strategies to Lower Your Premium
The easiest way to control renters insurance cost is to stop paying for a sloppy setup. Start with the policy structure, then ask for every discount that fits your household. A renter with solid claims history, basic safety devices, and a clean bundle opportunity can usually improve the price without cutting the protection that matters.
Ask for the discounts that make sense
Bundling renters and auto coverage is the first thing to check because it often gives you the cleanest path to a lower total bill. If you already carry auto insurance, bring both policies into the same quote conversation and see whether the combined structure improves the price. A local advisor can do that comparison without making you rebuild your coverage from scratch.
Also ask about discounts tied to security devices, deadbolts, monitored alarms, and a claims-free record. None of those should weaken the policy, and that is the point. You want the insurer to reward lower risk, not force you into a smaller claim payout later.
Use a higher deductible carefully
A higher deductible can reduce the premium, but do not use that tactic blindly. If your emergency fund is thin, a cheap policy with a painful deductible is not a bargain. Pick the deductible only after you know what you can comfortably absorb if the landlord says the unit is closed off or if a covered loss destroys a roomful of belongings.
If you want help comparing those tradeoffs with real market options, this Vero Beach home and auto bundle resource is useful because it focuses on the kind of multi-policy savings Florida households use. A quote review from an independent agency can also show whether a small premium increase buys you meaningfully better terms.
Best practice: compare total protection, not just the monthly number.
Professional Insurance Advisors, LLC can also quote renters coverage as part of its Florida personal lines work, which is useful when you want a single conversation about renters, auto, and coastal risk. The advantage is not hype, it is access to more than one carrier and a cleaner comparison of what each policy gives up or keeps.
How to Build a Home Inventory and File a Claim Successfully
A claim is easier when you already proved what you owned. Florida regulators specifically tell renters to inventory personal property by listing each item, its purchase date, purchase price, and serial number if available. That is not busywork, it is the difference between a smooth settlement discussion and a long fight over what was in the unit before the loss. Florida renters insurance toolkit
Start the inventory before you need it
Walk the apartment room by room and document what matters. Take photos, record serial numbers, and save receipts if you have them. A phone video is useful too, because it gives you a fast visual record of the unit and the contents inside it.
Store the inventory somewhere outside the rental. If the place floods, burns, or is left uninhabitable, a paper list inside the unit helps nobody. Cloud storage or a secure email copy works better because you can pull it up when the claim starts moving.
File fast and document everything
After a covered loss, report it immediately. Tell the carrier what happened, when it happened, and what was damaged, then keep a written log of every call, email, and inspection. The adjuster needs facts, not a story that changes every time new damage shows up.
Keep the inventory, photos, and claim notes together in one digital folder.
Do not toss damaged property too early unless the insurer tells you to. Photos can help, but the actual item can still matter during inspection. A well-documented claim is usually faster, cleaner, and easier to settle because the carrier can see exactly what you lost and why the numbers add up.
Getting a Personalized Quote from a Vero Beach Insurance Advisor
Buying renters insurance online can get you a price. It does not always get you the right coastal setup. A local independent agency understands which parts of a Vero Beach rental risk profile need a second look, especially the flood gap, the deductible structure, and whether bundling will save money without stripping out needed protection. Vero Beach insurance agency
Professional Insurance Advisors, LLC has served Florida households since 1985, and its approach fits renters who want a real comparison instead of a one-size-fits-all quote. If you want to check options, use the agency's online quote tools, the Quick Insurance Finder, or ask for a personalized review before you bind coverage. A short conversation can save you from discovering the wrong exclusion after a storm has already done the damage.
If you rent in Vero Beach, get the policy checked before the next storm watch, not after. Professional Insurance Advisors, LLC can help you compare renters coverage, spot the flood gap, and line up a quote that fits both your lease and your coastal risk.