
Professional liability insurance for CPA firms, often known in the industry as Errors and Omissions (E&O) insurance, is a specialized policy designed to protect your accounting practice from claims of negligence, errors, or omissions in your professional work. Think of it as an essential safeguard against the potentially devastating financial fallout of defending your firm and paying for damages, particularly within Florida's dynamic legal environment.
Why Florida CPAs Need Professional Liability Insurance
Imagine a simple calculation error on a tax return that costs a client thousands in IRS penalties. For a certified public accountant in Florida, this isn't a hypothetical nightmare–it's a real-world risk. Professional liability insurance acts as your practice's financial shield against these and other professional missteps.
This coverage isn't just another business expense; it's fundamental equipment for any modern accounting firm operating in the Sunshine State. With Florida's complex tax codes, demanding clients, and a rise in lawsuits, this protection is the bedrock of a secure and resilient practice.
The Growing Need for Protection
The modern financial world is loaded with risk, and CPAs are often on the front lines. The increasing complexity of regulations means that even the most meticulous professional can make a mistake. A single oversight can trigger a client lawsuit, leading to enormous legal fees, potential settlements, and serious reputational damage.
This heightened risk environment is clearly reflected in the global market for CPA liability insurance. This market was valued at $3,439.08 million in 2021 and is projected to surge to $4,185 million by 2025. This growth underscores the rising demand for coverage as firms scramble to protect themselves from an increasingly litigious landscape.
Your professional liability policy is the financial backstop that allows you to focus on serving your Florida clients without the constant fear of a lawsuit derailing your business. It covers defense costs, settlements, and judgments related to your professional services.
Mitigating Your Firm's Risks
While insurance is your ultimate financial shield, proactive risk management is your first line of defense. Implementing strong internal controls and maintaining clear client communication can dramatically reduce the chances of a claim ever happening.
Key strategies for risk reduction include:
- Detailed Engagement Letters: Always use comprehensive engagement letters that clearly define the scope of work, responsibilities, and deliverables for every single client project. No exceptions.
- Robust Internal Controls: Implement a system of checks and balances for all work, especially in high-risk areas like tax preparation, auditing, and advisory services.
- Clear Communication Protocols: Maintain transparent and documented communication with clients. This helps manage expectations and prevents the misunderstandings that often lead to disputes.
To help mitigate potential liabilities and ensure every client relationship starts on solid ground, some CPAs are even using tools like a free AI contract generator to help draft comprehensive engagement agreements. Ultimately, combining smart business practices with solid insurance coverage provides the most robust defense for your Florida CPA firm, ensuring its longevity and your personal peace of mind.
How Your CPA Insurance Policy Actually Works
To really get the value of professional liability insurance, you need to look past the jargon and see how a policy actually performs when you need it most. At the end of the day, this coverage is the financial backstop that kicks in when a client claims negligence, an error in your work, or a professional omission. It's what pays for the staggering costs of a legal defense, settlements, and court-ordered judgments.
The single most important thing to grasp is how the policy is structured. Nearly all professional liability policies for CPAs are written on a claims-made basis. This detail is critical because it dictates exactly when and how your coverage applies.
Understanding Claims-Made vs. Occurrence Policies
The best way to think about a claims-made policy is to compare it to a subscription service, like Netflix or Spotify. You are covered for any claims that are both made against you and reported to your insurer while your policy "subscription" is active. If you cancel your policy, your coverage for all your past work vanishes–unless you take specific steps to extend it.
This is completely different from an occurrence policy, which you typically see with general liability insurance. An occurrence policy is more like a lifetime warranty for a specific incident. It covers events that happen during the policy period, no matter when the claim is actually filed, even if it's years down the road.
For a Florida CPA, this distinction is everything. A simple tax error you make today might not be discovered by a client for two or three years. The claims-made structure means you need continuous, uninterrupted coverage to stay protected against those past actions.
To give you a clearer picture of the two, here's a side-by-side comparison:
Claims-Made vs. Occurrence Policies at a Glance
| Feature | Claims-Made Policy (Standard for CPA E&O) | Occurrence Policy (Common for General Liability) |
|---|---|---|
| Coverage Trigger | The claim must be made and reported during the active policy period. | The incident must occur during the policy period, regardless of when the claim is made. |
| Past Work | Covers past work back to a specific "retroactive date" as long as the policy is active. | Covers incidents that happened during the policy period, even after it expires. |
| Continuity | Requires continuous coverage. A gap can leave past work uninsured. | Coverage for a specific period is locked in, even if you switch carriers or retire. |
| Cost | Premiums start lower and increase over time as exposure to past work grows. | Generally more expensive upfront because the risk to the insurer has no time limit. |
Understanding this table is key to managing your firm's long-term risk. For CPAs, the claims-made model makes continuous coverage a non-negotiable part of doing business.
The growing awareness of these risks is reflected in the market itself. The CPA liability market is expanding, showing just how many firms are waking up to these exposures.
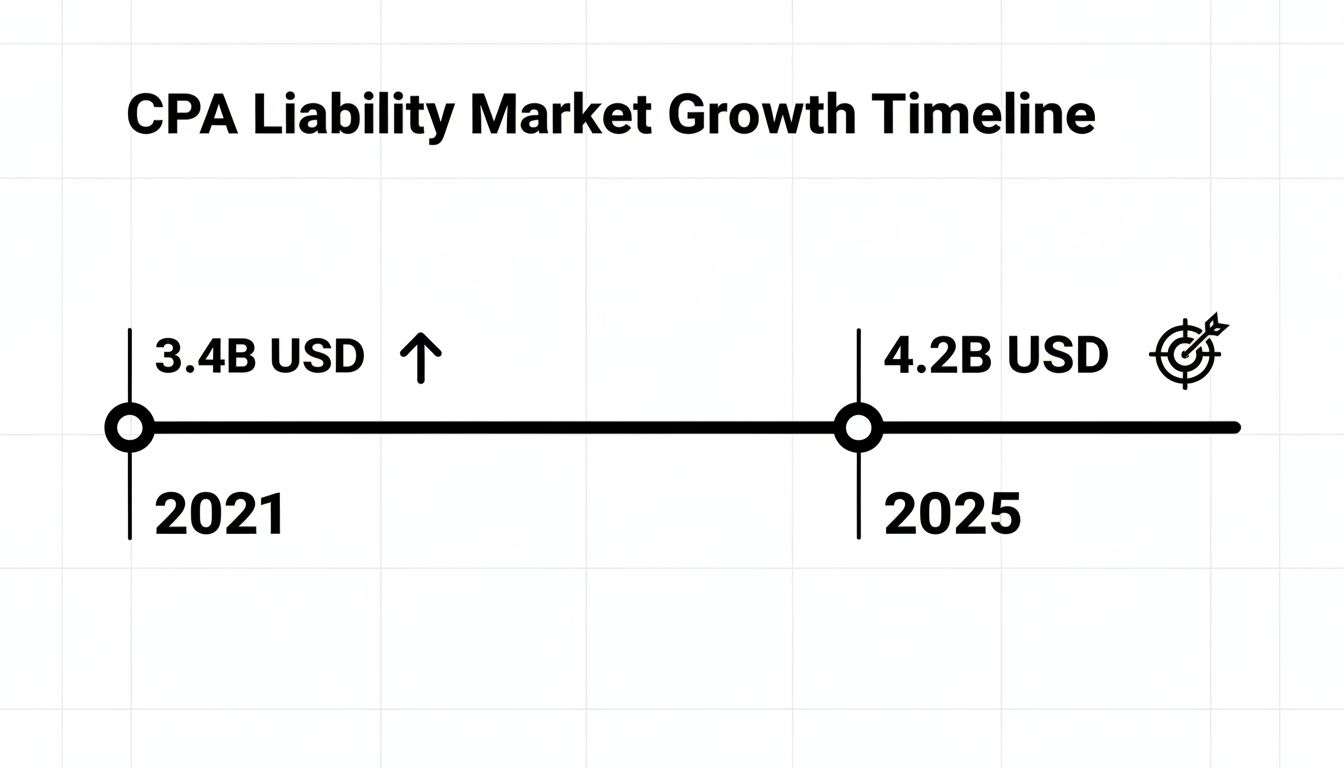
With the market projected to hit over $4.2 billion by 2025, it's clear that securing coverage is becoming standard practice, not an optional extra.
Key Concepts in Your Claims-Made Policy
To properly manage a claims-made policy, you have to know two concepts that define the boundaries of your protection: the retroactive date and your policy limits.
Retroactive Date: This is one of the most important dates on your policy. It sets a hard cutoff, meaning the policy will not cover any services you provided before this date. Think of it as the official start line for your firm's insurable history.
Policy Limits: These numbers define the maximum amount your insurer will pay out for a claim. You'll usually see them written as two figures, like $1 million / $2 million.
- The first number ($1 million) is the per-claim limit–the most your insurer will pay for any single claim.
- The second number ($2 million) is the aggregate limit–the total amount your insurer will pay for all claims combined within a single policy year.
It is absolutely essential to maintain your retroactive date when you switch insurance carriers. Allowing this date to move forward is like hitting a delete button on the coverage for your past work, creating a massive and dangerous gap in your firm's protection.
Choosing the right limits depends on your firm's size, the kind of services you provide, and your overall risk exposure. As you can find out more about in our guide, selecting the right CPA errors and omissions insurance is one of the most important decisions you'll make for your business. Working with an experienced agent in Florida can help you analyze your specific needs and lock in the right level of protection for your practice.

Common Claims and Critical Policy Exclusions
Knowing the structure of a professional liability policy is one thing. Seeing it jump into action during a real-world crisis is another entirely. For a Florida CPA, these risks aren't just hypotheticals–they're woven into the fabric of your daily work.
A single missed deadline, a piece of misunderstood advice, or an undiscovered error can quickly escalate into a claim that threatens your firm's stability. Let's break down how professional liability insurance for cpa practices actually responds when things go wrong.
How Your Policy Responds to Common Claims
Imagine a client in Miami follows your firm's tax planning advice and makes a major investment. A few months later, they discover a recent change in tax law invalidated your strategy, costing them a substantial amount of money. Naturally, they sue your firm for negligence.
This is where your professional liability insurance kicks in. It funds your legal defense, covering attorney fees, court costs, and any potential settlement or judgment, right up to your policy's limit. Without it, your firm would face these costs alone–a bill that can easily hit six figures even for a minor dispute.
Here are a few other all-too-common scenarios and how your policy helps:
- Missed IRS Deadline: Your firm accidentally files a corporate tax return late, and the client gets hit with thousands in penalties and interest. Your policy can cover the costs to make that client whole again.
- Failure to Detect Fraud: During an audit for a Fort Lauderdale business, your team doesn't uncover an employee's embezzlement scheme. When it's discovered later, the owner sues your firm for failing to perform your duties. Your E&O insurance would fund your legal defense.
- Data Breach Liability: A hacker breaches your network and steals sensitive financial data from dozens of clients. If your policy includes cyber liability, it helps cover client notification, credit monitoring, and legal defense if you're sued for not protecting their information.
The risk landscape is constantly shifting. We're seeing a surge in both the frequency and severity of claims, forcing carriers to raise premiums. This trend is driven by new regulations, complex data privacy laws, and updated financial reporting standards that create more opportunities for error.
Understanding Critical Policy Exclusions
Just as important as knowing what your policy covers is understanding what it does not. It's a dangerous and costly mistake to assume your E&O policy is a catch-all for every possible business risk. Every policy has specific exclusions, and knowing them is key to building a truly solid risk management plan.
Many claims arise from mistakes in financial reporting, which is why creating accurate balance sheets for small business is so critical. Yet even here, certain actions are explicitly excluded from coverage.
Think of it this way: professional liability insurance is designed to cover honest mistakes and professional negligence. It's not a get-out-of-jail-free card for criminal acts, intentional wrongdoing, or risks that belong under a different type of policy.
Here are the common exclusions you'll find in nearly every CPA E&O policy:
- Fraudulent or Criminal Acts: If you or an employee intentionally commits fraud, embezzles funds, or engages in criminal activity, your policy won't provide a defense or pay a claim.
- Bodily Injury or Property Damage: If a client slips and falls in your office or you damage their property, that's a job for your General Liability policy, not E&O.
- Employment-Related Disputes: Lawsuits from employees over things like wrongful termination or discrimination fall under a separate Employment Practices Liability Insurance (EPLI) policy.
- Personal Profit or Advantage: Your policy will not cover claims that arise from you gaining an illegal personal profit or advantage from a client engagement.
By understanding these common claims and exclusions, Florida CPAs can see exactly where their E&O policy protects them and where they might have gaps. You can learn more about how to handle potential claims against accountants in our detailed guide. This knowledge empowers you to build a more resilient firm, ready for whatever challenges come your way.
Taking on Florida-Specific CPA Risks
Working as a CPA in Florida isn't like practicing anywhere else. The risks you face are shaped by our state's unique economy and legal landscape. One day you might be advising a hotel on complex sales tax issues, and the next, you're helping a construction firm navigate the financial aftermath of a hurricane. Your professional liability has a distinctly local feel.
Getting this right is what separates an okay insurance policy from one that genuinely protects your practice. Your coverage needs to be built for the realities of the Sunshine State's dynamic–and sometimes litigious–market.
Matching Your Coverage to Florida's Economy
Florida's economy runs on a few key industries, and each one brings specific risks for accountants. A CPA in Orlando advising theme parks and hotels faces entirely different challenges than one in a state built on manufacturing. Your professional liability insurance has to reflect these local nuances.
Here are a few of Florida's key risk areas for CPAs:
- Hospitality and Tourism: Advising hotels, restaurants, and attractions means wading into complex sales tax laws, thorny employment issues, and tricky revenue recognition.
- Real Estate and Construction: Our booming real estate market creates a ton of exposure, from transaction advisory and cost segregation studies to the unique financial reporting that comes with construction projects.
- International Business: Many Florida businesses have deep ties to Latin America and the Caribbean. This brings intricate cross-border tax and compliance work, which is a common source of complex, high-stakes claims.
- Disaster Recovery: After a hurricane, businesses rely on you for critical financial guidance. Helping them document losses for insurance claims or federal aid is a high-pressure service where a single mistake can be devastatingly costly.
The insurance market understands these regional pressures. While North America as a whole drives the market due to the sheer number of CPA firms and strict regulations, Florida is its own ecosystem. It's why finding specialized coverage is so important. For the many mid-sized firms that are the backbone of our economy, a policy with $1-5 million in coverage is a common choice. Partnering with an expert like Professional Insurance Advisors gives business owners in Vero Beach and beyond access to competitive carriers who actually get these local risks. You can get more information on these CPA liability market trends.
Why Cyber Liability is Non-Negotiable in Florida
For any Florida CPA, one of the most immediate and dangerous risks is cyber liability. Think about the data you handle every single day–Social Security numbers, bank accounts, sensitive business plans. That information is a goldmine for criminals, and a data breach can sink your firm's finances and reputation overnight.
Florida has its own tough rules for data breaches, making solid cyber coverage a necessity, not just a nice-to-have. The Florida Information Protection Act (FIPA) imposes strict requirements on businesses after a breach, including tight deadlines for notifying every person affected.
Your standard professional liability policy might offer a little bit of coverage for a data breach, but it's nowhere near enough. A dedicated Cyber Liability policy is what you really need. It's designed to cover the big costs, like notifying clients, paying for credit monitoring, hiring a PR firm to manage your reputation, and covering legal defense if you get sued.
Without this dedicated coverage, a single cyber-attack could rack up expenses well into the six figures, putting your entire practice on the line. For any CPA in Florida, strong professional liability insurance for cpa work has to be paired with an equally strong cyber policy. It's the combination that creates a real shield against the biggest modern threats you face.

How to Secure the Right CPA Insurance
Diving into the insurance market can feel like a chore, but getting the right professional liability insurance for cpa firms doesn't have to be complicated. The goal isn't just to buy a policy; it's to become an informed buyer who can lock in great protection at a competitive price.
Think of it as preparing a presentation for the insurance company's underwriters. These are the people who evaluate your firm's risk and set your premium. A little preparation goes a long way and can make a real difference in the quotes you get back.
Your Step-by-Step Purchasing Checklist
To get the ball rolling, you'll need to pull together some key details about your practice. Having everything ready ahead of time makes the application process much smoother and ensures you receive the most accurate quotes possible. This is your chance to put your firm's professionalism on full display.
Here's a simple checklist to get you started:
- Gather Your Firm's Vitals: Collect essential information like annual revenues for the last few years, a list of all professional staff, and a clear breakdown of the services you offer. Also, have details ready about your current risk management procedures.
- Honestly Assess Your Risks: Take a hard look at where your biggest exposures lie. Are you handling high-stakes audits, complex tax advisory work, or clients in notoriously litigious industries? Knowing your unique risks helps you select the right coverage limits.
- Find an Independent Agent: This is a game-changer. Partnering with an independent agent, like our team at Professional Insurance Advisors, means you're not stuck with one company's offerings. We shop your application to multiple carriers to find the best policy and price for your Florida firm.
- Complete the Application with Care: Your insurance application is the primary document underwriters use to size up your firm. Be honest and thorough. Any inaccuracies or missing information could lead to a denied claim when you need your coverage most.
Key Factors Influencing Your CPA Liability Premium
Once your application is in, it lands on an underwriter's desk. Their job is to analyze your firm's risk profile and calculate a fair premium. Just like you review a client's financial health, an underwriter reviews your firm's operational health. They're looking for signs of a well-run, low-risk practice.
Several key factors heavily influence their decision-making. We've outlined them below so you know exactly what underwriters are looking for.
| Factor | Why It Matters | How to Manage It |
|---|---|---|
| Services You Offer | High-risk work like audits or M&A advisory carries more exposure than bookkeeping or basic tax prep. | Be clear about your service mix. If you take on high-risk work, highlight your expertise and specific controls for those engagements. |
| Internal Controls | Strong quality controls, like a second-partner review on complex jobs, show underwriters you're serious about preventing errors. | Document your review processes. A formal, written procedure for quality assurance is a major plus. |
| Engagement Letters | These documents set clear expectations and define the scope of work, which can prevent many disputes from escalating into claims. | Use them for 100% of engagements. This is one of the strongest signals of a well-managed firm you can send. |
| Claims History | Your firm's track record is a direct indicator of future risk. A clean history leads to better pricing. | If you have past claims, be prepared to explain what happened and what steps you've taken to prevent similar issues from recurring. |
| Annual Revenue | Higher revenue often means larger clients and more complex work, which increases potential liability. | Ensure your revenue figures are accurate. This helps underwriters place you in the correct risk category. |
Ultimately, a well-organized and transparent approach is your best strategy. By understanding what underwriters value, you can present your firm in the best possible light.
Think of the underwriting process as an open-book test. By showcasing your firm's strengths–like solid internal controls and disciplined use of engagement letters–you can directly influence your premium and secure better terms.
Being prepared pays off. By following this checklist and understanding what drives your costs, you put your Florida firm in a prime position to get the best professional liability coverage available. To get a better feel for how these factors translate into real numbers, take a look at our guide on the average cost of professional liability insurance for accountants.
Answering Your Top CPA Insurance Questions
Even after you've got the basics down, a few practical questions always pop up when it's time to buy or renew a policy. We get it. Here are the answers to the questions our Florida CPA clients ask us most, designed to give you the confidence you need to navigate the insurance process.
How Much Does Professional Liability Insurance for a CPA Cost in Florida?
The cost of professional liability insurance for cpa firms in Florida isn't a one-size-fits-all number; it really depends on the unique profile of your practice. A solo practitioner with a straightforward book of business might find a policy for as little as $500 annually. In contrast, a mid-sized firm in a major hub like Miami or Tampa could easily see premiums of $5,000 or more.
Several key factors will shape your final premium:
- Your Firm's Revenue: Higher revenue typically means greater exposure, which translates to higher premiums.
- Services Offered: If you're handling high-risk services like audits, M&A advisory, or complex forensic accounting, your costs will be higher than for a firm focused on standard tax prep and bookkeeping.
- Coverage Limits: It's simple math–a policy with a $2 million aggregate limit will cost more than one with a $500,000 limit.
- Claims History: A clean track record without any past claims will definitely earn you more favorable pricing from insurers.
Your firm's internal risk management also plays a big role. Insurers see practices that consistently use detailed engagement letters and have a documented second-partner review process as lower risks. An independent agent can dive into your specific profile to find the most competitive rate for the protection you truly need.
What Is the Difference Between Professional and General Liability?
This is one of the most common points of confusion we clear up for clients, and it's absolutely critical to get right. The easiest way to think about it is this: Professional Liability protects your brain, while General Liability protects your building and body.
Professional Liability Insurance, which you'll also hear called E&O insurance, is for financial losses your clients might suffer because of your professional mistakes. It's designed to cover claims that come from:
- Negligence in your work
- Incorrect tax advice
- An error or omission in financial statements
General Liability Insurance, on the other hand, is all about physical risks. It kicks in for claims of:
- Bodily injury (e.g., a client trips over a power cord in your office and breaks their arm).
- Property damage (e.g., one of your staff spills coffee on a client's expensive laptop).
- Personal and advertising injury (e.g., your firm gets sued for slander).
Both policies are non-negotiable for a CPA firm in Florida. They cover entirely different worlds of risk and you can't substitute one for the other.
Do I Still Need Insurance If I Retire or Sell My Practice?
Yes, you absolutely do. This is a crucial detail that many accountants miss. Because professional liability is a "claims-made" policy, the policy has to be active when the claim is filed, not just when the work was done. If you just cancel your policy when you retire, you leave yourself completely exposed to lawsuits for all the work you did in the past.
A mistake you made five years ago could be discovered tomorrow, but if you don't have an active policy, you'll have zero coverage for the lawsuit that follows.
To protect yourself, you need to purchase an Extended Reporting Period (ERP), better known as "tail coverage." This endorsement extends the timeframe you have to report claims that come from work you did before you retired. It's the only way to shield your personal assets from your past professional acts.
Doesn't My LLC or S-Corp Protect My Personal Assets?
Forming an LLC or S-Corp is a smart first step, but it doesn't give you total immunity from professional negligence lawsuits. The "corporate veil" is meant to shield your personal assets from business debts and the company's general liabilities. However, courts have repeatedly shown that it doesn't typically protect you from claims of your own professional malpractice.
If a client sues your firm and names you personally for a mistake you made, a court can still come after your personal assets–your home, savings, and investments are all on the line.
Professional liability insurance for CPAs is specifically designed to close this critical gap. It protects both the business entity and the individual professionals working within it from the staggering costs of legal defense and judgments. It's the final layer of security that your corporate structure alone can't provide, making sure both your firm and your family are properly safeguarded.
At Professional Insurance Advisors, LLC, we understand the unique risks facing Florida CPAs. With over 120 years of combined experience, our team helps firms across the state secure the right protection. Let us help you safeguard your practice. Start your free quote today.