
Bailment Agreement: Top 3 Critical Insights
Understanding Bailment Agreements: When Property Changes Hands
A bailment agreement occurs when you temporarily transfer possession of property to another person without transferring ownership. Whether you are handing client tax documents to a colleague, storing equipment at a repair shop, or leaving your car with a mechanic, you are entering into a bailment relationship.
Key Elements of a Bailment Agreement:
- Bailor – The person who owns and delivers the property
- Bailee – The person who receives and temporarily holds the property
- Personal property – Must be moveable goods (not real estate)
- Temporary possession – Property must be returned to the owner
- Specific purpose – Clear reason for the transfer (storage, repair, safekeeping)
- No ownership transfer – Title remains with the original owner
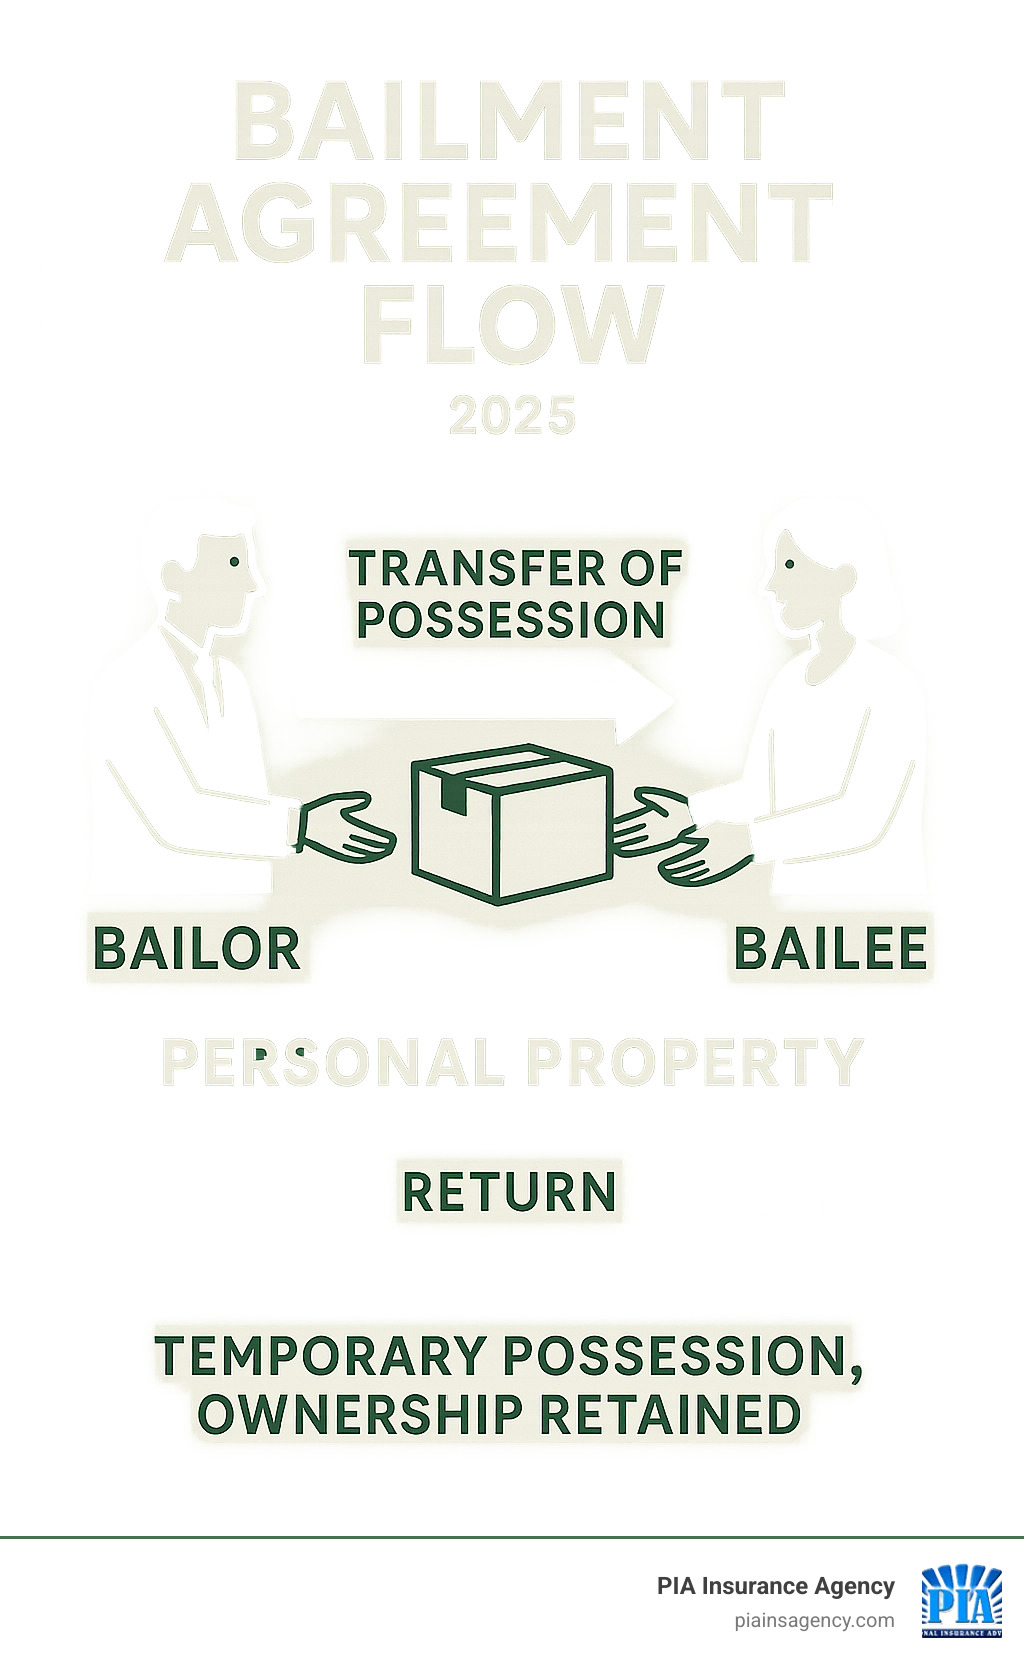
This infographic shows how property flows from bailor to bailee and back, with possession transferring but ownership remaining unchanged.
For accounting professionals in Florida, bailment agreements present unique risks. When you handle client documents, store financial records, or manage sensitive data, you become a bailee with specific legal duties and potential liabilities.
I’m Patti Yencho. With over 26 years of experience helping Florida businesses with complex insurance needs, I have seen how bailment agreement situations can create unexpected exposures for accounting firms. Understanding these relationships is crucial for protecting your practice and ensuring you have the right coverage in place.
What is a Bailment? Core Components and Key Distinctions
At its heart, a bailment is a legal relationship where physical possession of personal property is temporarily transferred from one party (the bailor) to another (the bailee) for a specific purpose. While possession changes hands, legal ownership, or title, remains with the bailor.

A bailment begins when the bailor delivers an item to the bailee, who knowingly accepts possession. The understanding is that the bailee will guard the property with reasonable care and return it once the purpose is fulfilled. Checking a book out from a library is a perfect example of a bailment.
For a more comprehensive legal understanding, you can refer to A clear definition of bailment.
To truly grasp the nuances of a bailment agreement, it is helpful to compare it with other common arrangements involving property.
| Arrangement | Purpose | Ownership | Possession | Common Use Case |
|---|---|---|---|---|
| Bailment | Temporary care, repair, storage, use | Retained by Bailor | Transferred to Bailee | Valet parking, dry cleaning, mechanic repair |
| Consignment | Sale of goods | Retained by Consignor | Transferred to Consignee | Art galleries, used car dealerships, apparel stores |
| Lease | Exclusive use for a specified period | Retained by Lessor | Transferred to Lessee | Apartment rental, car lease, equipment rental |
| License | Permission to use property, no control | Retained by Licensor | No transfer of control | Parking a car in an unattended lot, software EULA |
The Essential Elements of a Valid Bailment
For a bailment agreement to be legally recognized, several essential elements must be present:
- Parties: There must be a clear Bailor, the owner who delivers the property, and a Bailee, the party who receives temporary possession.
- Personal Property: Bailments only apply to personal property-movable goods, not real estate. This includes items like your client’s financial documents or a vehicle.
- Delivery of Possession: The bailor must physically or constructively deliver the property to the bailee. Constructive delivery might be handing over the keys to a storage unit.
- Acceptance by Bailee: The bailee must knowingly accept possession of the property. If you leave your coat in a restaurant and no one takes responsibility for it, a bailment might not be formed. However, if a waiter offers to store it, acceptance is implied.
- Specific Purpose: The transfer must be for a defined reason, such as storage, repair, transportation, or temporary use.
- No Transfer of Title: This is paramount. The bailor retains full legal ownership of the property.
- Obligation to Return: The bailee must have an obligation to return the property to the bailor or dispose of it according to the bailor’s instructions once the purpose is fulfilled.
Legally, bailment is distinct from a sale and is broadly related to UCC Article 2 (Sale of Goods).
Bailment vs. Consignment: A Critical Distinction for Professionals
While both bailment and consignment involve transferring goods without transferring ownership, their purposes are fundamentally different. This distinction is critical for professionals in inventory management or sales.
A bailment agreement is for an express purpose like safe storage, repair, or improvement. For example, if a manufacturer sends parts to a third party for assembly and the assembled product is returned, that is a bailment. The intent is not to sell the parts to the assembler.
On the other hand, a consignment arrangement occurs when one party (the consignor) provides goods to another (the consignee) to sell on their behalf. The consignor retains ownership until the goods are sold, and the consignee then pays the consignor from the proceeds. Consignment is common for items like apparel or furniture, allowing retailers to avoid buying large inventories upfront.
The key takeaway is the purpose of transfer:
- Bailment: Temporary possession for a specific task (storage, repair, use) without the intent of sale.
- Consignment: Temporary possession specifically for the purpose of sale.
This difference in intent affects which Uniform Commercial Code (UCC) articles govern these arrangements. While bailment broadly relates to UCC Article 2, consignment often falls under UCC Article 9 (Secured Transactions). Understanding this distinction means recognizing different risks and legal protections.
Types of Bailments and the Bailee’s Standard of Care
Not all bailments are created equal. The bailee’s level of care, and potential liability, varies depending on who benefits from the bailment agreement.

Generally, there are three types of bailments, each carrying a different “standard of care” that the bailee must exercise. If the bailee fails to meet this standard, they could be found negligent and held liable for any damage or loss.
For the Mutual Benefit of Both Parties
This is the most common type of bailment agreement in business, often called a “bailment for hire” or “service agreement bailment.” In these scenarios, both the bailor and bailee receive a benefit. The bailor benefits from the service (e.g., storage, repair), and the bailee benefits from compensation.
In Florida and across the U.S., bailees in a mutual benefit bailment must exercise “reasonable care”. This means protecting the property with the same care a prudent person would use for their own belongings.
Examples include:
- Dropping off clothes at a dry cleaner’s.
- Leaving your car with a mechanic for repairs.
- Paying for a storage unit.
- Using a paid valet parking service.
- Placing valuables in a bank’s safe deposit box.
For accounting professionals, storing physical client documents or data on a server for which clients pay a fee creates a mutual benefit bailment. Our responsibility is to exercise reasonable care in safeguarding those assets. This is where specialized coverage, like Understanding Bailee Coverage: A Complete Guide, becomes relevant.
For the Sole Benefit of the Bailor
In this type of bailment agreement, the bailee receives no compensation for holding the property; they are doing the bailor a favor. This is often called a “gratuitous bailment.”
Since the bailee acts without compensation, the law imposes a lower standard of care. The bailee must exercise “slight care” and is typically only liable for “gross negligence” or willful misconduct. For example, holding a former client’s old tax documents as a favor makes you a gratuitous bailee. You would not be expected to guard them like a bank vault, but you could not intentionally destroy them.
For the Sole Benefit of the Bailee
Conversely, when the bailee is the only party who benefits from the bailment agreement, they are held to the highest standard of care. This occurs when someone borrows property without offering anything in return.
In these situations, the bailee must exercise a “high degree of care” and is often held to “strict liability” for any damage. This means they might be liable even if they were not negligent. Imagine borrowing a friend’s specialized accounting software or a high-end server for a project. You would be expected to treat it with extreme caution, knowing that any damage would likely be your responsibility.
Understanding these varying standards of care is crucial for accountants, especially when handling diverse client property, from physical records to digital data.
Your Comprehensive Bailment Agreement: Rights, Duties, and Liabilities
A well-structured bailment agreement is a critical tool for defining expectations, rights, and liabilities. While many bailments are informal, a clear, written agreement is essential in professional contexts to prevent disputes.
The legal implications are significant, especially regarding liability. In Florida, these agreements are governed by common law and interact with statutes like The 2024 Florida Statutes covering warehousing.
Rights and Responsibilities of the Bailor and Bailee
Both parties in a bailment agreement have distinct rights and responsibilities:
Bailor’s Rights:
- Right to Have Property Returned: To have property returned in its original condition (less normal wear and tear) after the bailment’s purpose is fulfilled.
- Right to Compensation: To seek compensation if the property is damaged or lost due to the bailee’s negligence.
- Right to Limit Use: To specify how the bailee may use the property. Any unauthorized use can lead to liability for the bailee.
- Right to Terminate: To terminate the agreement if the bailee breaches its terms or misuses the property.
Bailor’s Responsibilities:
- Duty to Disclose Defects: Must inform the bailee of any known defects in the property that could cause harm.
- Duty to Provide Instructions: Should provide clear handling instructions for property requiring specific care.
- Duty to Reclaim Property: Must reclaim their property once the bailment purpose is complete.
Bailee’s Rights:
- Right to Possession: To temporarily possess the property for the agreed-upon purpose.
- Right to Reimbursement: To be compensated for services rendered or expenses incurred in a mutual benefit bailment.
- Right to Stop Delivery: May have the right to retain property if the bailor fails to meet obligations (like payment), sometimes through a possessory lien.
- Right to Limit Liability: To contractually limit liability, provided the limitations are reasonable and clearly stated. Learn more in our Bailee Definition article.
Bailee’s Responsibilities:
- Duty of Reasonable Care: Must exercise the appropriate standard of care for the property.
- Duty to Follow Instructions: Must adhere to the bailor’s instructions on the use and care of the property.
- Duty to Safekeep: Must protect the property from theft, damage, or loss within their control.
- Duty to Return Property: Must return the property to the bailor once the bailment ends.
- No Unauthorized Use: Must not use the property for any purpose other than what was agreed upon. Unauthorized use can constitute “conversion,” a serious legal offense.
Understanding Liability in a Bailment Agreement
The question of “who is responsible when things go wrong?” is central to any bailment agreement. A bailee’s liability typically arises from:
- Negligence: The most common basis for liability. If the bailee fails to exercise the required standard of care and the property is damaged, they are liable.
- Breach of Contract: If the bailee violates the agreement’s terms (e.g., unauthorized use), they can be held liable for breach of contract.
- Conversion: This occurs when the bailee unlawfully uses or disposes of the property in a way that is inconsistent with the bailor’s ownership rights.
A bailee is generally not liable for damages from unforeseen events (like natural disasters) if they exercised proper care. However, if their negligence contributed to the loss, they can be held liable.
Bailees can limit their liability through clauses in the agreement. These “exculpatory clauses” can reduce responsibility for certain losses, but they cannot absolve the bailee from gross negligence. Florida courts scrutinize such clauses to ensure they are clear and not against public policy.
For unclaimed property, the bailee must follow a legal process, which may include selling the property to recover fees, but they must adhere to statutory requirements.
When Does a Bailment Agreement End?
A bailment agreement is temporary and can terminate in several ways:
- Purpose Fulfilled: The bailment ends when its specific purpose has been accomplished.
- Time Expiration: The agreement ends when its specified duration expires.
- Mutual Agreement: Both parties can agree to terminate the bailment at any time.
- Destruction of Property: If the bailed property is destroyed, the bailment ends.
- Breach of Terms: If either party breaches a significant term, the other may have grounds to terminate it.
- Bailor’s Demand: In a gratuitous bailment, the bailor can typically demand the property’s return at any time.
Upon termination, the bailee must return the property to the bailor.
Mitigating Risk: The Crucial Role of Insurance in Bailment
For businesses handling client property, the liabilities associated with a bailment agreement can be significant. Standard general liability policies often have a “care, custody, or control” exclusion, meaning they do not cover damage to property temporarily in your possession. This is a significant blind spot for many businesses.
For accounting professionals in Florida, this exclusion is particularly pertinent. When you take possession of client documents or hard drives with sensitive data, you become a bailee. The risk extends beyond physical damage to data breaches, loss of records, and professional negligence.
What is Bailee’s Liability Insurance?
This is where specialized coverage steps in. Bailee’s liability insurance is designed to cover property belonging to others that is in your care, custody, or control. It protects businesses from loss or damage to customers’ property due to perils like fire, theft, or natural disasters.
Think of it as a safety net for when you are acting as a bailee. It covers your legal liability for damage to customers’ property while it is in your possession. This is distinct from standard business insurance, which covers your own property. If a fire in your office destroys client files, What is Bailee Coverage? would be the policy that responds. You can also explore specific options like Bailee Insurance to tailor coverage to your needs.
Crafting a Protective Bailee Contract
While insurance is a financial safety net, a well-drafted bailment agreement is your first line of defense. We always recommend written agreements for business transactions. A written agreement clearly defines:
- The Parties and Property: Who is the bailor and bailee, and what property is being bailed.
- Purpose and Duration: The reason for the bailment and how long it will last.
- Bailee’s Responsibilities: The standard of care, handling instructions, and any use limitations.
- Limiting Liability Clauses: These are crucial for capping damages or limiting liability for certain losses.
- Indemnification: Clauses where one party agrees to protect the other from loss.
- Return Conditions: How and when the property will be returned.
A robust Bailee Contract manages expectations, clarifies duties, and provides a legal framework to resolve disputes, reducing your risk.
Errors & Omissions (E&O) Coverage for Accountants
For accounting professionals, a bailment agreement often overlaps with professional services. While bailee’s liability insurance covers physical property, what about the invaluable “property” of client data and financial records?
This is where Errors & Omissions (E&O) coverage, or professional liability insurance, is paramount. E&O insurance protects accounting firms against claims of professional negligence, errors, or omissions.
Consider this:
- If you misplace a client’s physical tax documents, bailee’s liability insurance might cover the cost of recreating them.
- But if a professional error in handling those documents leads to financial losses for your client, that falls under professional negligence, covered by E&O.
- Handling sensitive client data involves a fiduciary responsibility. A data breach can lead to significant liability, which E&O policies are increasingly designed to address.
At PIA Insurance Agency, we focus on custom risk management solutions for accounting practices. We understand your responsibilities extend beyond the tangible. Ensuring you have comprehensive coverage for both physical property (bailee’s liability) and professional acts (E&O) is key to securing your practice in Florida.
Frequently Asked Questions about Bailment Agreements
To help clarify this legal concept, here are some common questions we hear about bailment agreements.

What is the main difference between bailment and consignment?
The core difference is purpose. Bailment is for temporary possession for a specific task like storage or repair, with the property returned to the owner. Consignment is for the purpose of sale, where the consignee sells goods on behalf of the consignor. The intent for the goods-service vs. sale-sets them apart.
Is a bailee automatically liable for any damage to bailed property?
No. A bailee’s liability depends on the type of bailment and the required standard of care. They are liable only if they fail to meet that standard (i.e., are negligent). They are not typically liable for damages from unforeseen events if they exercised appropriate care. For instance, a storage company is not liable for hurricane damage if it took reasonable precautions, but it is liable if its negligence (like leaving a door open) contributed to the loss.
Can a bailment exist without a written contract?
Yes. A bailment can be created by an oral agreement or implied by the actions of the parties, such as handing your keys to a valet. However, a written bailment agreement is always recommended for clarity and legal protection, especially in business. A written agreement minimizes misunderstandings and provides clear evidence of the terms.
Conclusion: Securing Your Practice with Smart Agreements and Coverage
Bailment agreements are more common than many realize, impacting our personal and professional lives. From leaving a laptop with a technician to an accounting firm managing client data, understanding the nuances of bailment is essential.
For accounting professionals in Florida, recognizing your role as a bailee is a fundamental aspect of risk management. The standard of care you must provide can vary, and your liabilities can be significant. This is why clear, written agreements are a necessity.
It is also vital to have the right insurance coverage. Standard policies often leave gaps for property in your care, custody, or control. Specialized bailee’s liability insurance, coupled with robust E&O coverage, creates a comprehensive shield for your practice.
At PIA Insurance Agency, we pride ourselves on helping professionals in Miami, Orlando, and across Florida steer these complex waters. We help you identify your unique exposures and tailor insurance solutions that truly protect your firm.
Here are our key takeaways for navigating bailment successfully:
- Always use a written bailment agreement for business bailments, clearly defining terms and liabilities.
- Know the standard of care you must provide as a bailee, as it changes based on the type of bailment.
- Ensure your insurance covers property in your care, custody, and control.
- Review your policies to understand the interplay between Bailee Coverage and E&O insurance.
Do not leave your practice vulnerable to unforeseen risks. Learn how specialized Bailee Coverage can protect your accounting firm today.