
Accountant E&O Insurance: Crucial for 2025 Protection
Why Professional Liability Protection Is Essential for Florida’s Financial Professionals
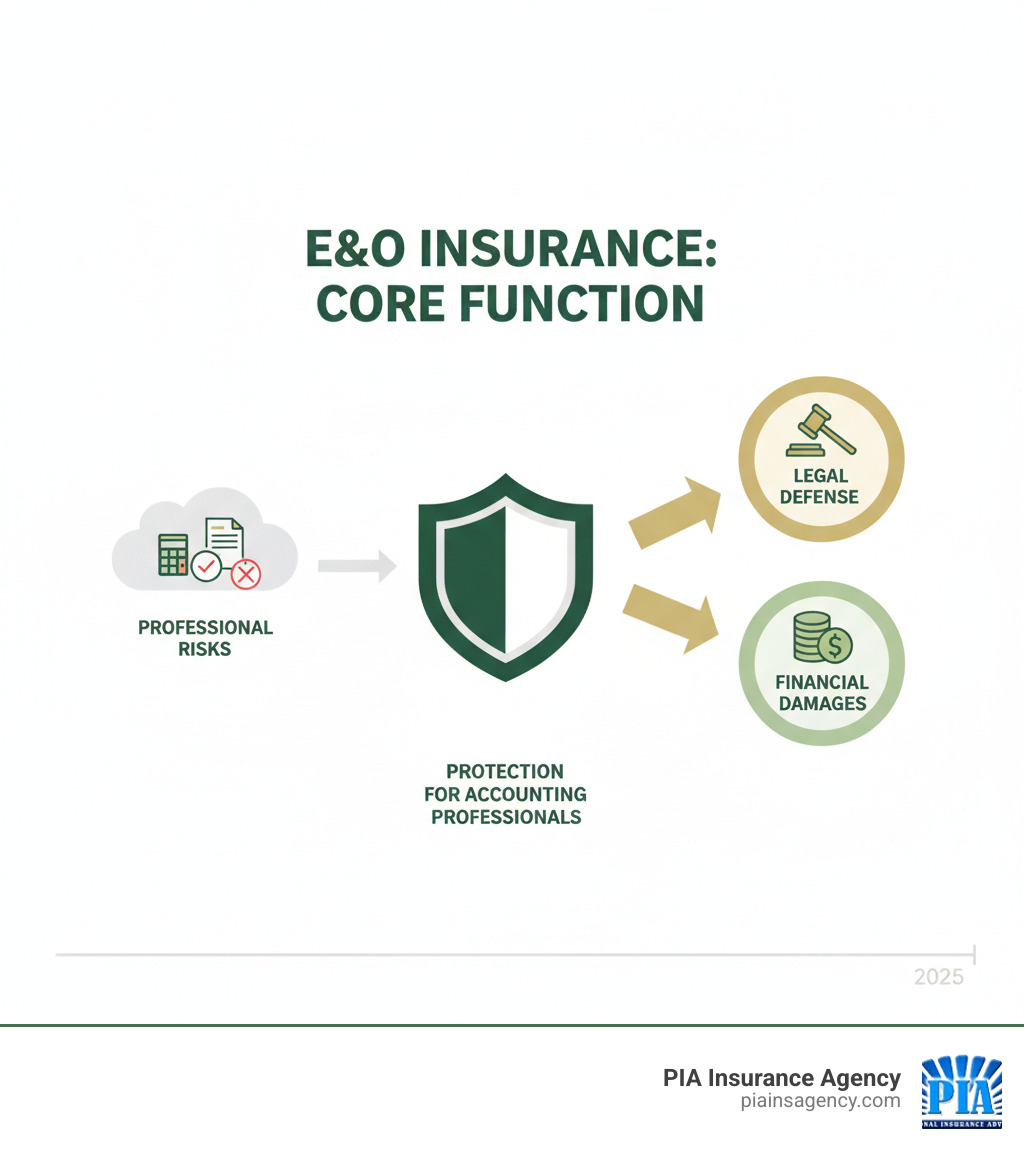
Accountant E&O insurance protects accounting professionals from financial losses when clients sue over alleged errors, omissions, or negligent acts in professional services. This coverage pays for legal defense costs and damages, even when claims are groundless.
Key Benefits of Accountant E&O Insurance:
- Legal Defense Coverage – Pays attorney fees and court costs
- Damage Protection – Covers monetary judgments and settlements
- Professional Mistakes – Protects against tax errors, missed deadlines, and audit mistakes
- Negligence Claims – Defends against accusations of inadequate service
- Regulatory Proceedings – Covers disciplinary actions and investigations
Consider an accounting firm owner who faced a lawsuit over an unintentional tax filing error that led to hefty IRS penalties for a client. Without E&O insurance, the firm was exposed to substantial legal fees and reputational damage.
The reality is stark: finance and accounting businesses pay a median of less than $35 per month for professional liability insurance, yet defense costs alone can be financially devastating. In Florida’s competitive business environment, where client expectations are high and lawsuits are common, even meticulous professionals face exposure to costly liability claims.
I’m Patti Yencho, and over 26 years of serving Florida families and businesses, I’ve seen how accountant E&O insurance protects practices from career-ending financial risks. My whole-life approach to risk management helps accounting professionals build comprehensive protection that keeps pace with their growing practices.
What is E&O Insurance and Why Is It Crucial for Accountants?
Imagine a client claims your tax advice cost them thousands in penalties. Even if you followed every procedure correctly, you now face a lawsuit that could drain your savings and damage your reputation.
This is why accountant E&O insurance exists. Also known as professional liability insurance, it protects you when clients claim your services caused them financial harm due to alleged negligence, errors, or omissions.
The protection goes beyond obvious mistakes. A client might perceive an error even when you’ve done everything right. For Florida’s accounting professionals, this coverage is critical. Your policy covers legal defense costs plus any settlements or judgments, protecting your firm’s financial stability. It also helps preserve your professional reputation, as many clients now require their accounting firms to maintain E&O coverage.
Our comprehensive guide on Understanding the Importance of Accountant Professional Liability Coverage for Accounting Firms explores these protections in greater detail.
Specific Risks Covered by Accountant E&O Insurance
Accountant E&O insurance protects against real-world risks that accounting professionals face daily. Key covered scenarios include:
- Inaccurate advice: A client claims your financial guidance led to losses.
- Tax preparation mistakes: Filing errors, missed deadlines, or overlooked deductions trigger IRS penalties.
- Auditing errors: A missed discrepancy in financial statements leads to stakeholder losses.
- Misrepresentation: A client believes you presented incorrect information, even if unintentional.
- Data mismanagement: Poor record-keeping or lost documents disrupt a client’s business. While cyber liability insurance handles data breaches, E&O addresses professional errors in managing client information.
- Breach of contract: You allegedly failed to deliver services as promised in your engagement letter.
For detailed information about these protections, visit our page on Errors and Omissions Insurance for Accountants.
Common Claim Scenarios

Real-world scenarios illustrate how accountant E&O insurance protects your practice:
- Tax Filing Error: A CPA in Orlando accidentally submits a client’s payroll taxes one day late due to a calendar mix-up. The client demands reimbursement for the resulting IRS penalties.
- Flawed Financial Advice: A Miami accountant advises a client on business expansion. When the expansion fails due to an unforeseen market downturn, the client sues for negligent advice.
- Bookkeeping Mistakes: A bookkeeper transposes numbers in financial statements, leading a client to make a poor business decision based on incorrect data.
- Missed Deadlines: A Jacksonville firm fails to submit a client’s required SEC financial reports on time, leading to regulatory sanctions and a claim against the firm.
These scenarios show that professional liability risks are part of everyday practice. Accountant E&O insurance provides the protection that lets you serve clients confidently while safeguarding your financial future.
Decoding Your E&O Policy: Coverage, Limits, and Key Features
Understanding your accountant E&O insurance policy is about knowing how your professional safety net works. Most E&O policies are claims-made and reported, meaning a claim must be made against you and reported to your insurer during the policy period for coverage to apply.
Your policy will also have a retroactive date, which is the cutoff point for how far back your coverage extends. Any error made before this date won’t be covered, which is why maintaining continuous coverage is vital. Our CPA Errors and Omissions Insurance page explains more about this.
Key features to understand include:
- Coverage limits: The maximum amount the insurer will pay per claim and per policy period. We typically recommend starting at $1 million for solo practitioners, $1.5 million for firms with 2-3 members, and $2 million or more for larger firms.
- Deductible: The amount you pay before insurance coverage begins. A higher deductible can lower your premium, but ensure it’s an amount you can comfortably afford.
- Policy exclusions: These specify what isn’t covered, such as intentional fraud, criminal acts, or bodily injury.
- Endorsements: These are add-ons that customize your policy, such as regulatory proceedings coverage, subpoena assistance, or crisis event coverage for public relations help.
We work with carriers that offer policies where defense costs don’t erode your coverage limits, leaving the full amount available for settlements or judgments.
How E&O Differs From Other Business Insurance
An accounting practice needs several types of insurance. Accountant E&O insurance protects against professional mistakes, but it’s just one piece of the puzzle.
| Insurance Type | What it Covers | What it DOESN’T Cover | Common Triggers |
|---|---|---|---|
| Errors & Omissions (E&O) | Professional negligence, errors, omissions, or wrongful acts in your accounting services | Bodily injury, property damage, intentional criminal acts, employee theft | Client sues over tax error, missed deadline, incorrect advice, auditing mistake |
| General Liability (CGL) | Bodily injury, property damage, and advertising injury on your premises or from your operations | Professional errors, data breaches, employee injuries, auto accidents | Client slips in your office, you accidentally damage client property |
| Cyber Liability Insurance | Data breach costs, cyber-attacks, notification expenses, regulatory fines, business interruption | Professional errors, physical property damage, employee injuries | Network hack exposing client data, ransomware attack shutting down systems |
General liability covers everyday accidents, like a client slipping in your office. Cyber liability is essential for handling the costs of data breaches. These policies work as a team, with E&O acting as the quarterback protecting your professional services. You can explore our General Liability Insurance options to see how they work together.
Who Is Eligible for Accountant E&O Insurance?
If you provide financial advice or services that clients rely on, you are likely eligible for accountant E&O insurance. This includes:
- Certified Public Accountants (CPAs)
- Bookkeepers, who can make costly errors despite handling day-to-day records. Premiums for bookkeepers can start as low as $300 per year. Our Bookkeeper Insurance page has more details.
- Tax preparers, who face seasonal pressures and deadline-driven risks.
- Enrolled agents representing taxpayers before the IRS.
- Small to mid-sized accounting firms needing coverage that scales with their growth.
- Independent contractors who are personally liable for their services.
- Financial advisors and consultants who also provide accounting-related services.
The bottom line is simple: if a client could claim financial harm from your professional work, you need E&O insurance.
Factors Influencing the Cost and Requirements of E&O Coverage
The price of accountant E&O insurance is not a flat rate; it reflects your firm’s unique risk profile. Key factors include:
- Firm size: A solo practitioner in Miami FL will pay less than a ten-person firm in Orlando FL due to lower exposure.
- Services offered: Basic bookkeeping carries less risk and a lower premium than complex audits or forensic accounting.
- Annual revenue: Higher revenue often correlates with more clients and larger engagements, indicating greater risk.
- Claims history: A clean record lowers your premium, while past claims may increase it.
- Employee training and qualifications: Investments in continuing education and strong internal controls can help manage costs.
- Location: Florida’s legal environment and regional economic factors play a role in risk assessment.
- Coverage limits and deductibles: Higher limits increase cost, while a higher deductible can lower it.
- Risk management practices: Using engagement letters and peer review processes signals to insurers that you are proactive about preventing claims.
For more insights, explore our Professional Liability Insurance Cost guide.

Typical Costs and Minimum Limits
The good news is that accountant E&O insurance is more affordable than most professionals expect.
- For general accounting services, premiums can start around $700 per year for $1 million in coverage.
- For bookkeeping services, coverage can start from just $300 annually.
- The median cost for finance and accounting businesses is less than $35 per month, which is a small price for career-saving protection.
When choosing minimum coverage limits, consider these industry guidelines:
- Solo practitioners: At least $1 million in coverage.
- Firms with 2-3 members: At least $1.5 million.
- Firms with 4+ members: $2 million or higher.
These figures are based on claim analysis and professional recommendations. For a deeper dive, check our guide on the Average Cost of Professional Liability Insurance for Accountants.
Professional Body Recommendations
Professional accounting organizations take E&O insurance seriously.
CPA Canada, for example, mandates coverage based on firm size: $1 million for one-member firms, $1.5 million for two or three-member practices, and $2 million for firms with four or more members. Quebec has similar strict regulations, as seen in their Reglement sur l’assurance de la responsabilite professionnelle des comptables professionnels agrees.
While Florida state board regulations may not always mandate E&O insurance, it is strongly recommended and has become an expected standard. Furthermore, many client contracts now require proof of E&O coverage before an engagement begins, making it a necessity for winning business. This is a key part of comprehensive Risk Management for Accounting Firms.
Frequently Asked Questions about Accountant E&O Insurance
Over 26 years of helping Florida professionals, I’ve heard many questions about accountant E&O insurance. Here are answers to the most common concerns.
Is E&O insurance mandatory for accountants in Florida?
While Florida does not have a blanket state mandate requiring all accountants to carry accountant E&O insurance, it is often a practical necessity.
The Florida Board of Accountancy may require coverage for certain licensees or services. More importantly, client contracts frequently make it mandatory. Many businesses in Miami FL, Orlando FL, and across the state will not work with an accountant who lacks professional liability coverage.
From a best practices standpoint, carrying E&O insurance is the professional standard. While not always legally mandated, it is a contractual and professional requirement to stay competitive.
How much E&O coverage does my accounting firm need?
There is no one-size-fits-all answer. The right amount depends on a personalized risk assessment of your practice. Key factors include:
- Firm size: As a starting point, solo practitioners often need at least $1 million, while firms with 2-3 members should consider $1.5 million, and larger firms $2 million or more.
- Client profile: Serving high-net-worth individuals or large corporations increases potential claim sizes and may require higher limits.
- Complexity of services: Complex work like audits or forensic accounting carries higher risk than basic bookkeeping.
- Contractual requirements: Always check client agreements for specified minimum coverage limits.
A specialist broker can help you analyze these factors to determine the right coverage for your firm’s needs and budget.
Does E&O insurance cover employee theft or fraud?
This is an important distinction. Accountant E&O insurance covers professional mistakes, errors, and omissions-not intentional criminal acts by the insured.
For protection against employee theft or dishonesty, you need a separate policy called a Fidelity bond or Crime insurance. These are designed to cover losses when an employee steals money or property.
However, many E&O policies include an “Innocent Insured” provision. This can protect innocent partners in your firm from the wrongful acts of a colleague, provided they had no knowledge of the fraudulent activity. A comprehensive risk management strategy requires both E&O insurance for professional errors and crime coverage for employee dishonesty.
Conclusion: Securing Your Practice with the Right Partner
After exploring accountant E&O insurance, it’s clear this is not just another business expense-it’s the essential safety net for your practice. You’ve spent years building your expertise and reputation in Florida. A single claim, even if unfounded, can put it all at risk. For a median cost of less than $35 per month, this protection is a smart investment.
E&O insurance provides peace of mind, allowing you to focus on delivering excellent service without worrying about what might go wrong. It demonstrates your commitment to professional excellence and gives you the financial stability to thrive.
At PIA Insurance Agency, we don’t just sell policies; we build relationships. With 26 years serving Florida businesses, we understand that every practice has a unique risk profile. A solo tax preparer in Miami FL faces different challenges than a CPA firm in Orlando FL, and your coverage should reflect that. Our whole-life approach to risk management helps us craft coverage that grows with your business.
As experts in Professional Liability Insurance Brokers, we speak your language and understand your challenges. Don’t let another day pass with your practice exposed.
Ready to take the next step? Contact us for a custom E&O insurance quote custom to your accounting firm’s needs. Let’s work together to build the comprehensive protection that keeps your practice strong and your future secure.